13 London Road,
London, SE1 6JZ
020 7928 0276
[email protected]

News and Insights

When someone dies abroad leaving money, shares or a property in England and Wales, the grant of probate issued where they lived is often not enough on its own. UK banks and share registrars usually want to see an English grant, and HM Land Registry will not deal with property here without one. That is because a grant only gives authority in the country whose court issued it.

For some countries, you can ask the Probate Registry to reseal the grant you already have, instead of applying for a new English grant. That avoids a completely new application, but only certain countries’ grants qualify, and UK inheritance tax has to be dealt with first.
Namecard for article - Yi Ling English

Written by Yi Ling Lio, Private Client Paralegal


What does resealing a grant of probate mean?

The Probate Registry stamps the foreign grant with the seal of the Family Division of the High Court. From then on, it works in England and Wales as if a court here had made it. For example, the deceased may have lived in Hong Kong and had an account with a UK bank. Once the Hong Kong grant is resealed, the executor named in it can close that account, sell or transfer property, and deal with shares in the usual way.


Which countries’ grants can be resealed in England and Wales?

Resealing is only possible for grants from countries and territories covered by the Colonial Probates Acts 1892 and 1927. Most are current or former Commonwealth countries, including Hong Kong, Malaysia, Singapore, Australia, New Zealand, Canada and Kenya. South African grants can also be resealed, although South Africa is not on the list itself. You will find the full list at the end of this article.

In Australia and Canada, the list goes state by state or province by province, so every Australian state is covered but Quebec is not. No US state is on the list. Jersey, Guernsey and the Isle of Man are not on it either.

Grants from Scotland and Northern Ireland do not need resealing at all. As long as the grant notes that the person died domiciled there, it is recognised in England and Wales as it is.


What if the country is not on the list?

Grants from mainland China, Taiwan, India, the United States and most of Europe cannot be resealed. If the grant came from one of those countries, you will need to apply for a new grant in England and Wales.

Where the person died domiciled abroad, the English grant can go to one of three people:

  • the person put in charge of the estate by the court in the country of domicile
  • the person entitled to the estate under that country’s law
  • the executor named in the will, if the will is in English or Welsh


Depending on which of these applies, the registry may have to make an order first, and you may need evidence of the foreign law from a lawyer qualified in that country. All of this takes longer than a reseal, so check the list before you start.


Who can apply to reseal a grant?

The application is made by the person named on the foreign grant, or by someone they have authorised in writing. Executors living abroad often ask a solicitor here to apply for them, under a letter of authority or a power of attorney.

Unless a registrar agrees otherwise, the grant must have been made to one of the same three people listed above. That brings in domicile, which is a legal concept and not the same as nationality or where someone happened to be living. If there is any doubt about it, the registry may ask for evidence. Our article on Matyas v Daniel shows how closely the courts look at this.

If the grant was made to more than one person, the registry may ask about anyone who is not joining in the application, and a grant made to more than four people cannot be resealed. A grant that is limited, or only lasts for a set period, needs a registrar’s permission. And even where the country is on the list, the registrar can refuse a reseal and tell you to apply for a new English grant instead.


Inheritance tax comes first

The registry will not reseal a grant until UK inheritance tax has been reported and any tax due has been paid. This is usually the part that takes longest.

Which form you need depends on the person’s connection with the UK and what they owned here. For deaths on or after 6 April 2025, the test is long-term UK residence, which broadly means being UK resident for at least 10 of the previous 20 tax years. For earlier deaths, the test is domicile. If the person was neither, they are generally taxed only on what they owned in the UK, and that can still mean tax to pay.


IHT207, the short form. You can use this instead of a full account if all of the following apply:

  • the person was not a long-term UK resident when they died (or, for deaths before 6 April 2025, was domiciled abroad)
  • they had never been UK domiciled, deemed domiciled or long-term UK resident
  • their UK assets were only cash and quoted shares, worth no more than £150,000 in total before debts
  • they had not given away more than £3,000 a year of UK assets in the seven years before they died
  • they did not hold an indirect interest in UK residential property, such as a UK home owned through a company


IHT400, the full account. Any other estate needs a full IHT400 sent to HMRC. That includes an estate with UK property, such as a London flat, or shares in a private company, even if the estate is below the tax threshold and nothing is payable. Once HMRC has processed the IHT400, it sends a letter with a probate code and the estate figures. The registry needs that code before it will look at the application. (The code replaced the old IHT421 form in January 2024.)

Deadlines. Any inheritance tax is due by the end of the sixth month after the month of death. After that, HMRC charges interest, even if the executors cannot yet access the estate’s money. The IHT400 must be filed within 12 months of the end of the month of death, and filing late can lead to penalties. So in an estate that owes tax, the payment deadline often arrives before the reseal does.

Tax on UK property can usually be paid in ten yearly instalments, so the full amount is not due at once. Many UK banks and building societies will also pay inheritance tax straight to HMRC from the deceased’s own accounts before any grant is issued, under HMRC’s Direct Payment Scheme.


What documents do you need?

The reseal application is made on paper, not online. You will usually need:

  • the foreign grant: the original, a duplicate sealed by the court that issued it, a copy certified by that court, or an exemplification
  • the will, if the grant does not already include a copy, certified by the court that issued the grant, plus plain copies of both the grant and the will
  • form PA1P if there is a will, or PA1A if there is not
  • the IHT207, or HMRC’s letter with the probate code if you sent an IHT400
  • the letter of authority or power of attorney, if someone is applying on the grantee’s behalf
  • an English translation of the will, if it is not in English
  • the court fee


What if the grant or will is not in English?

Only grants issued in English, or in English alongside another language, can be resealed. If the grant is only in another language, resealing is not available and you will need to apply for a new grant in England and Wales.

A will that is not in English needs an English translation. The registry accepts a translation by an English notary under seal, or by a British consular official. A translation by anyone else, however fluent, is only acceptable if a district judge or registrar gives directions first.


How long does it take and what does it cost?

The registry fee is £526 if the estate in England and Wales is worth more than £5,000. It went up from £300 in July 2026. If the estate is £5,000 or less, there is no fee.

Extra sealed copies cost £2 each if you order them with the application, or £16 each if you order them later. Each bank or share registrar will usually want its own copy, so decide how many you need before you apply.

Most of the waiting is on the tax side, because HMRC has to process any IHT400 before the registry will look at the papers. Once that is done, allow around four to five months for the reseal itself. When the registry is satisfied, it reseals the grant, sends it back to you and tells the court abroad.

A reseal is not always quicker, though. The registry can be slower with reseals than with new English grants, and some banks see them less often and come back with more questions. For some estates, a new English grant ends up being the easier route. Take advice on which route suits the estate.


In summary

If someone has died abroad leaving assets here, two questions decide the route. Did the grant come from a country on the list, and is it in English? If both answers are yes, a reseal may work. If not, you will need a new English grant, and it is better to know that early.

Either way, inheritance tax comes first. The HMRC deadlines run from the month of death, whether or not your paperwork is ready.


How we can help

We act for executors abroad who need to deal with UK assets. We can check whether the grant can be resealed, deal with HMRC and the Probate Registry, and work alongside your lawyer abroad, in English, Mandarin or Cantonese. If there is UK property in the estate, get in touch early.


The list is in Schedule 1 to the Colonial Probates Act Application Order 1965, which still uses many old colonial names. Using today’s names, it includes:

  • Asia: Hong Kong (still covered after the 1997 handover), Malaysia, Singapore, Brunei and Sri Lanka
  • Australia and New Zealand: New Zealand, and in Australia all six states (New South Wales, Queensland, South Australia, Tasmania, Victoria and Western Australia), the Australian Capital Territory, the Northern Territory, Christmas Island, the Cocos (Keeling) Islands and Norfolk Island
  • Canada: Alberta, British Columbia, Manitoba, New Brunswick, Newfoundland and Labrador, Nova Scotia, Ontario, Prince Edward Island, Saskatchewan and the Northwest Territories
  • Africa: Botswana, Eswatini (Swaziland), The Gambia, Ghana, Kenya, Lesotho, Malawi, Nigeria, Seychelles, Sierra Leone, Tanzania, Uganda, Zambia and Zimbabwe
  • The Caribbean and Atlantic: Anguilla, Antigua, the Bahamas, Barbados, Belize, Bermuda, the British Virgin Islands, the Cayman Islands, Dominica, the Falkland Islands, Grenada, Guyana, Jamaica, Montserrat, St Helena, St Kitts and Nevis, St Lucia, St Vincent, Trinidad and Tobago, and the Turks and Caicos Islands
  • The Pacific: Fiji, Kiribati, Papua New Guinea, the Solomon Islands and Tuvalu
  • Europe and elsewhere: Gibraltar, the Republic of Cyprus, the British Sovereign Base Areas in Cyprus, and the British Antarctic Territory (grants from the Turkish Republic of Northern Cyprus cannot be resealed)


South Africa is not on the list, but South African grants can still be resealed.


Need legal advice? We’re here to help.

If you have questions about your situation or need advice on your next steps, our experienced legal team can help.

Call us on 020 7928 0276 between 9:30am and 6:00pm, or email [email protected].

You can also contact us online by completing our short enquiry form. Tell us a little about your situation and we’ll get back to you as soon as possible.

Not sure which service you need? Get in touch and we’ll help you identify the right team.

author avatar
James Cook

You have been told by the police to attend a custody suite. Perhaps the investigation has been continuing for some time and the police now want to deal with the allegation formally. The word “custody” immediately raises an obvious concern: if you go in, are you going to be allowed to go home?

Attending a custody suite does not itself mean that you will automatically be kept there. Depending on what happens, you may be charged and released, released subject to bail conditions, or kept in custody for a court appearance. The immediate question is therefore not only what you are accused of, but also what information is available to show why you should be allowed to leave on bail.

White Namecard for article - Paul Cheuk in English (1)

Written by Paul Cheuk, Solicitor


Speak to a Solicitor Before You Attend

If the police ask you to attend a custody suite, we suggest obtaining legal advice immediately rather than waiting until you arrive. A person detained at a police station has the right to consult a solicitor privately, and free independent legal advice is available at the police station.

A solicitor can help to establish what the police intend to do and advise you about the likely procedure. More importantly, the solicitor can start thinking about matters which you may not yet have considered, including whether bail is likely to become an issue and what information should be available to address it.

There is an important practical advantage in speaking to the solicitor before attendance. It gives time to prepare rather than trying to obtain addresses, employment documents or other information after the client is already inside the police station.


The Police Know the Allegation Better Than They Know You

By this stage, the police may know a great deal about the alleged offence. They may have statements, messages, CCTV or other material collected during the investigation. What the custody officer may know much less about is your personal life.

When someone is about to be charged, almost all of their attention naturally goes to the allegation. They are thinking about what happened, what the witnesses have said, what messages exist and how the allegation can ultimately be defended.

Those issues are important, but they may not be the first issue that needs to be dealt with that afternoon. Before any trial takes place, somebody may first have to decide whether you are going home.

Do you have a permanent home in the UK? How long have you lived there? Do you have stable employment? Does your spouse or your children live here? Do you operate a business? Do you care for somebody? Have you attended voluntarily whenever the police asked you to do so?

These matters can be important when considering whether there is any genuine reason to believe that you would disappear, fail to attend court, commit another offence or interfere with the case. If bail has not been considered in advance, one may suddenly find themselves trying to remember an employer’s details, explain where they live, identify evidence of their family circumstances while already inside a custody suite without the help of the phone or internet.


Your Address Can Become Material

Something as ordinary as where you live can suddenly become highly relevant. A person who has lived at the same address for many years may be able to demonstrate a strong connection with the area. If someone has no settled address, or their living arrangements are unclear, the police may have more questions about where that person will be if released.

Depending on the circumstances, it would be helpful to have simple evidence available. This could include a tenancy agreement, council tax bill, mortgage statement or other document showing where the client actually lives.

It is not a question of arriving with a suitcase full of paperwork. The useful documents will depend on the particular concern which might arise.


Work and Family Can Help Show Your Connection to the UK

Employment may also be important. Someone with permanent employment, a business, professional responsibilities or regular working commitments in this country may have obvious reasons to remain here and attend court.

Family circumstances can also form part of the picture. A person whose spouse, children and home are all in the UK may be able to demonstrate substantial connections with this country.

Again, the evidence may be straightforward. A recent payslip, employment contract, company record or evidence of family responsibilities may sometimes be useful.

It is much easier to produce that material if somebody has thought about it before the client attends the police station.


What If You Have Connections Overseas?

Having family, nationality, property or business interests overseas does not mean that bail will automatically be refused. Many people living in the UK naturally have significant connections with other countries.

However, if the police are concerned that someone may leave the country rather than attend court, overseas connections may become relevant.

The complete picture therefore matters. How long have you lived in the UK? Where is your main home? Where do you work? Where does your immediate family live? Have you complied with previous police requests? Have you previously travelled while under investigation and returned when required?

Where foreign travel is the particular concern, surrendering a passport may sometimes be considered as a bail condition. The important question is whether a practical condition can address the perceived risk rather than whether detention is necessary simply because the client has an overseas connection.


Prepare Before You Walk Through the Door

When a client tells us that the police have asked them to attend a custody suite, our work should begin before the attendance itself.

We want to understand what the police intend to do, advise the client about the process, consider the allegation and prepare for any interview. We also want to know where the client lives, what they do for work, what family responsibilities they have, how strong their connections are with the UK, whether there are significant overseas connections and whether they have previously complied with police or court requirements.

At Lisa’s Law, when assisting clients who are asked to attend a police station or custody suite, we do not wait for the bail question to arise before thinking about it. Defending the allegation is important, but so is the immediate question of liberty. Preparing for both before attending can make a significant practical difference.


Need legal advice? We’re here to help.

If you have questions about your situation or need advice on your next steps, our experienced legal team can help.

Call us on 020 7928 0276 between 9:30am and 6:00pm, or email [email protected].

You can also contact us online by completing our short enquiry form. Tell us a little about your situation and we’ll get back to you as soon as possible.

Not sure which service you need? Get in touch and we’ll help you identify the right team.
author avatar
James Cook

Buying a home is a major commitment, and circumstances can change during the conveyancing process. A survey may reveal unexpected problems, mortgage funding may fall through, or the buyer may reconsider.

In England and Wales, the consequences largely depend on whether contracts have been exchanged.

Before exchange, withdrawing usually means losing money already spent. After exchange, it can lead to substantial financial liability.

Namecard for article - John in English 1

Written by John Ju, Conveyancing Paralegal

Before Exchange: Generally Free to Withdraw

Before exchange of contracts, an accepted offer is usually “subject to contract”. Neither party is legally committed to completing the transaction. A buyer can generally withdraw without compensating the seller simply for changing their mind. The seller can also withdraw or accept another offer.

However, withdrawing is unlikely to be cost-free. The buyer may have already paid for searches, a survey, mortgage arrangements and legal work. Whether any fees are refundable depends on the provider’s terms and the work completed.

The seller may also incur wasted expenses and delays, particularly where the withdrawal disrupts a chain. In an ordinary transaction, these losses do not automatically become the buyer’s responsibility before exchange.

Separate agreements may change the position. A reservation or exclusivity agreement, for example, may impose payment obligations or limit refunds. Buyers should obtain legal advice before entering into such agreements and check the terms before withdrawing.

After Exchange: A Binding Commitment

Exchange of contracts creates a legally binding agreement to buy and sell the property. Both parties commit to the contract terms, including the completion date. There is generally no cooling-off period, and changing your mind does not release you from your obligations.

A buyer who withdraws without a valid legal or contractual basis risks losing their exchange deposit, commonly 10% of the purchase price. On a £400,000 purchase, this could mean £40,000. Depending on the contract conditions, paying a smaller deposit does not necessarily limit liability to the amount paid.

The financial consequences may extend beyond the deposit. The seller may claim compensation for recoverable losses caused by the breach, potentially including a

shortfall if the property is subsequently sold for less. Any claim must be supported by evidence and assessed under the contract and applicable law.

If completion is delayed, contractual interest may also become payable. The seller may serve a notice to complete, setting a final deadline for completion. Under the Standard Conditions of Sale, this is normally ten working days, excluding the day the notice is given. Failure to comply may allow the seller to terminate the contract, retain the deposit and pursue damages.

What Should a Buyer Do If a Seller Pulls Out?

Before exchange, a seller can generally withdraw without compensating the buyer for costs already incurred. If this happens, contact your conveyancer and estate agent to confirm the seller’s position and establish whether the transaction can still proceed. Your conveyancer can also check whether any separate reservation or exclusivity agreement gives you rights or remedies.

After exchange, the seller is legally bound by the contract and cannot simply withdraw because they have changed their mind. Contact your conveyancer immediately if the seller refuses or fails to complete. Depending on the circumstances and the contract terms, your options may include agreeing a revised completion date, serving a notice to complete or pursuing legal remedies.

If the seller fails to comply with a valid notice to complete, you may be entitled to terminate the contract, recover your deposit and claim damages for recoverable losses. In some cases, it may also be possible to seek a court order requiring the seller to complete the sale. Your conveyancer can advise on the appropriate steps before you agree to any cancellation or commit to another purchase.

What Should a Seller Do If a Buyer Pulls Out?

A buyer pulling out can be stressful, particularly if you are relying on the sale to fund your next purchase. Your first step should be to contact your conveyancer and establish whether contracts have been exchanged, as this determines your rights and the options available.

Before exchange, ask your estate agent to confirm why the buyer has withdrawn and whether the problem can realistically be resolved. If the purchase will not proceed, discuss putting the property back on the market and contacting other interested buyers. Tell your conveyancer promptly if the withdrawal affects a related purchase, so they can review your commitments and help you manage the impact on the chain. Although you may have incurred wasted costs, these are not ordinarily recoverable from the buyer unless a separate agreement provides otherwise.

After exchange, seek legal advice before agreeing to cancel the sale, returning any deposit or committing to sell to someone else. Your conveyancer can assess whether the buyer has a valid basis for withdrawing and advise on the appropriate response, which may include negotiating a short extension, serving a notice to complete or pursuing contractual remedies.

Keep copies of relevant correspondence and records of any additional expenses or losses. If the contract is lawfully terminated and you seek compensation, you will generally need to take reasonable steps to limit your losses, such as remarketing the property promptly. Any claim should reflect recoverable losses and account for any deposit retained.

If you need advice or assistance, please contact us here. Our team will be happy to help.

Need legal advice? We’re here to help.

If you have questions about your situation or need advice on your next steps, our experienced legal team can help.

Call us on 020 7928 0276 between 9:30am and 6:00pm, or email [email protected].

You can also contact us online by completing our short enquiry form. Tell us a little about your situation and we’ll get back to you as soon as possible.

Not sure which service you need? Get in touch and we’ll help you identify the right team.
author avatar
James Cook

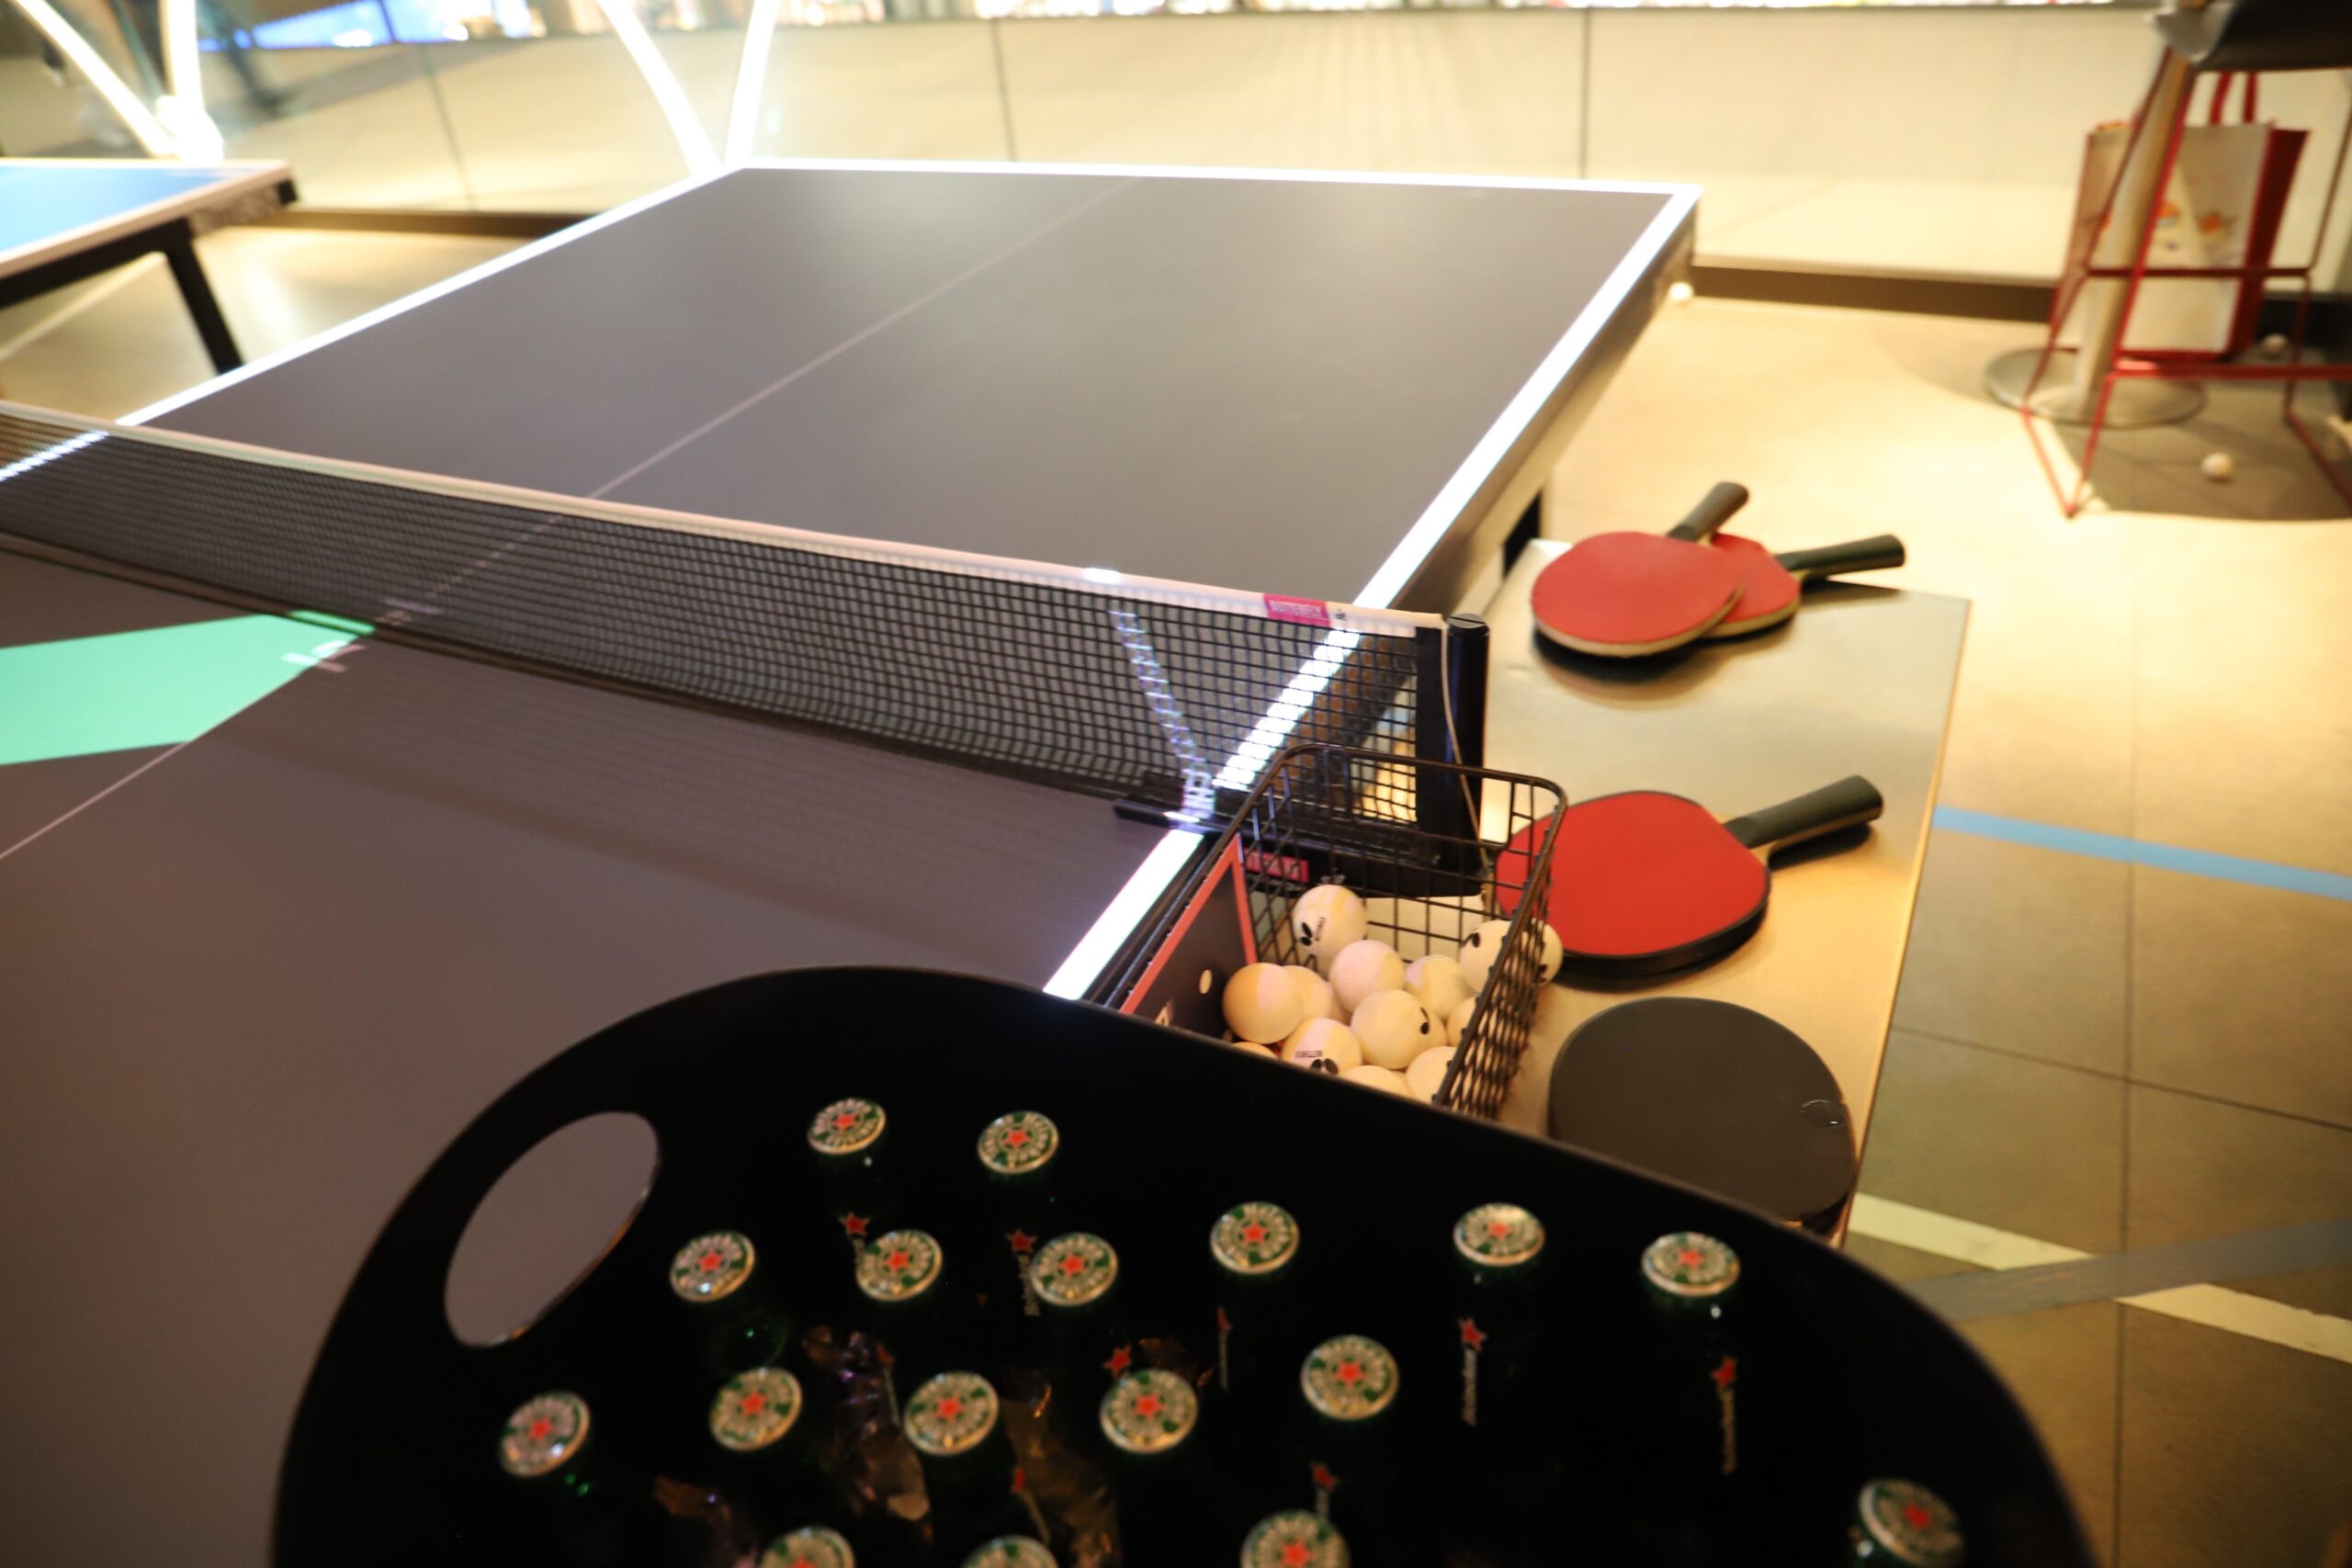
Lisa’s Law staff and business partners alike recently gathered on Friday 16 October for our Autumn Social at Bounce in the impressive Battersea Power Station, for an evening of food, drinks, networking and friendly competition.

Coming together outside of work is an important part of life at Lisa’s Law. With office-based and remote colleagues across several departments, events like this give us the chance to reconnect and build relationships that a busy London law firm doesn’t always leave time for.

We were also delighted to welcome some of our closest business partners from companies including Oceantide, ChaseEvans, Chestertons, Tai Bong, Chancery Consultants Ltd and Barrain London. A relaxed setting like this makes it easier to catch up, exchange ideas and strengthen the working relationships we value.


Table tennis tables with colleagues in the background


On arrival, we were met with beer, wine, food and more while everyone mingled. We then split into pairs to take part in a table tennis tournament organised by the friendly Bounce staff.

People playing table tennis

The tournament was highly competitive, with colleagues and business partners alike coming together to try and win.

Thank you to everyone who came, including our business partners. We are already looking forward to our next event, our Christmas social later this year.

You can find out more about our last Summer social here and our Spring social here.


Need legal advice? We’re here to help.

If you have questions about your situation or need advice on your next steps, our experienced legal team can help.

Call us on 020 7928 0276 between 9:30am and 6:00pm, or email [email protected].

You can also contact us online by completing our short enquiry form. Tell us a little about your situation and we’ll get back to you as soon as possible.

Not sure which service you need? Get in touch and we’ll help you identify the right team.
author avatar
James Cook

Many people assume that a spouse, partner or adult child can automatically manage their money and make decisions for them if they become unwell. In England and Wales, that is not the case. However, without a lasting power of attorney (LPA), no one has automatic legal authority to act for an adult who can no longer make their own decisions.

This article explains what family members and others can and cannot do in that situation, and what you can do now to avoid problems later.

Namecard for article - Xinlei Zhang in English

Written by Xinlei Zhang, Senior Associate Solicitor


Capacity comes first

Under the Mental Capacity Act 2005, every adult is presumed to have mental capacity unless it is shown otherwise. Capacity is assessed for each decision at the time it needs to be made. Someone may be able to decide what to eat but not be able to understand the risks of selling their home.

While you have capacity, you can make your own decisions, and you can appoint others to help. The difficulty arises when capacity is lost, for example through dementia, a stroke or a serious accident.


What family members cannot do

Even a husband, wife or civil partner has no automatic right to:

  • access or manage your bank accounts held in your sole name
  • sell or remortgage your property
  • deal with your pension, investments or insurance
  • make financial decisions on your behalf
  • instruct professionals such as solicitors or accountants for you


Banks and other organisations will normally refuse to deal with someone who does not have formal legal authority.


What is still possible without an LPA

Joint accounts and existing arrangements. If you hold a joint bank account, the other account holder can usually continue to use it, depending on the bank’s terms. This does not cover accounts or assets held in your sole name. Direct debits and standing orders that were already set up will normally keep running.

Third-party mandates. Some banks allow a person with capacity to give a trusted person limited access to an account. These arrangements are generally intended for use while you have capacity, and a bank may stop honouring them once it knows you have lost capacity. They are not a substitute for an LPA.

Benefits appointees. If you receive state benefits, including the State Pension, the Department for Work and Pensions can appoint someone to manage those benefits for you. An appointee can deal only with the benefits, not your wider finances.

Day-to-day care and treatment. The Mental Capacity Act allows carers, family members and professionals to do reasonable things in connection with someone’s care or treatment, provided they believe the action is in that person’s best interests. For medical treatment, doctors make decisions in the patient’s best interests and are expected to consult family and others close to the person. Family members do not have the power to consent to or refuse treatment on the person’s behalf unless they hold a health and welfare LPA.


Applying to the Court of Protection

If there is no LPA and the person has lost capacity, the usual route is an application to the Court of Protection. The court can:

  • appoint a deputy, usually for property and financial affairs. Deputies for health and welfare decisions are appointed only in limited circumstances.
  • make a one-off order about a specific decision, such as selling a property.
  • authorise a statutory will where the person cannot make a valid will themselves.


This route has drawbacks compared with an LPA:

  • Time. Applications can take several months. Urgent applications are possible in some circumstances, but you should not rely on that.
  • Cost. Court fees apply, and deputies usually have to pay for a security bond and ongoing supervision fees. Fees are set by the court and the Office of the Public Guardian and change from time to time, so check the current figures on GOV.UK.
  • Oversight. A deputy is supervised by the Office of the Public Guardian, must keep accounts and submit annual reports, and may need court approval for certain decisions.
  • Choice. The court decides who the deputy will be. It may not be the person you would have chosen.
  • Control. A deputy’s powers are set by the court order and are usually narrower than those given under an LPA.


What you can do now

If you still have capacity, you can put arrangements in place before they are needed:

  • Make lasting powers of attorney. There are two types: one for property and financial affairs, and one for health and welfare. You choose who acts for you and can set conditions. An LPA must be registered with the Office of the Public Guardian before it can be used, and registration takes time, so it is better to do this early.
  • Consider an advance decision. This lets you refuse specified medical treatment in advance. It has to meet legal requirements, particularly for refusing life-sustaining treatment.
  • Write down your wishes. A statement of your preferences for care is not legally binding but must be taken into account when decisions are made in your best interests.
  • Review your will. An LPA ends on death, and a will deals with what happens afterwards. Both matter.


You can make an LPA only while you have capacity to understand what you are signing. If capacity has already been lost, the Court of Protection route is likely to be the only option.


Key points

  • No one, including a spouse or adult child, automatically has legal authority to manage another adult’s affairs.
  • Joint accounts, benefits appointeeships and day-to-day care decisions offer limited help but do not replace an LPA.
  • A Court of Protection application is possible but is generally slower, more costly and more restrictive than an LPA.
  • An LPA can only be made while you have capacity, so the best time to arrange one is before you need it.


Speak to a solicitor

Every situation is different. An LPA is an important safeguard, helping to ensure that decisions about your health, welfare, property and finances are made by people you trust and, so far as possible, in accordance with your wishes. Loss of capacity can occur unexpectedly and at any age, so putting an LPA in place in advance can provide valuable reassurance. If you expect your health to deteriorate, it is particularly important to make arrangements as early as possible.

We offer fixed fees. Our standard fees are:

  • One LPA – £750 plus VAT
  • Two LPAs (one person making both types) – £1,050 plus VAT
  • Four LPAs (a couple making both types at the same time) – £1,680 plus VAT


Additional charges may apply where instructions are more complex, depending on your circumstances. A registration fee of £92 per LPA is also payable to the Office of the Public Guardian.

If you want to make a lasting power of attorney, or you are worried about a relative who has lost capacity, our team at Lisa’s Law Solicitors can explain the options and the next steps.

Find out more about our Lasting Powers of Attorney service here and contact us to arrange an initial conversation.


Need legal advice? We’re here to help.

If you have questions about your situation or need advice on your next steps, our experienced legal team can help.

Call us on 020 7928 0276 between 9:30am and 6:00pm, or email [email protected].

You can also contact us online by completing our short enquiry form. Tell us a little about your situation and we’ll get back to you as soon as possible.

Not sure which service you need? Get in touch and we’ll help you identify the right team.
author avatar
James Cook

Buying or selling a home involves several important steps. Two key moments are exchange of contracts and completion. Understanding what happens at each stage can help you plan your move and know what to expect.

Namecard for article - Stephanie Chow in English

Written by Stephanie Chow, Solicitor


What happens before exchange?

Before contracts can be exchanged, the buyer’s conveyancer will usually complete the necessary anti-money laundering checks, review the title documents and search results, deal with enquiries, and report to the buyer. If the buyer is using a mortgage, the conveyancer will also check the mortgage arrangements.

Both parties need to agree the contract terms and a completion date. The buyer should make sure they understand the purchase, have their deposit ready and have arranged any necessary buildings insurance.

Until exchange, either party can usually withdraw from the transaction. An agreed offer by itself does not make the sale legally binding.


What does exchange of contracts mean?

At exchange, the conveyancers formally exchange the contracts signed by the buyer and seller. The agreement becomes legally binding, and the completion date is fixed. If either party fails to complete as required by the contract, this may amount to a breach of contract and have financial or other legal consequences.

The buyer will usually pay a deposit on exchange. The amount and arrangements can vary, so the buyer should confirm with their conveyancer how much is required and when it must be sent.

If you are buying and selling at the same time, the transactions may be linked in a chain. Your conveyancer will coordinate exchange with the other conveyancers so that the linked transactions can proceed together.


What happens between exchange and completion?

The time between exchange and completion varies. During this period, the buyer should:

  • arrange removals and prepare for the move;
  • send any remaining money needed for completion to their conveyancer in good time;
  • check arrangements for collecting the keys; and
  • confirm with their conveyancer whether buildings insurance needs to be in place from exchange.


The buyer’s conveyancer will request the mortgage funds, carry out any remaining pre-completion checks and prepare the completion arrangements. The seller should make arrangements to move out and ensure the property is ready to hand over in line with the contract.


What happens on completion day?

On the agreed completion date, the buyer’s conveyancer sends the purchase money to the seller’s conveyancer. Once the money has arrived and completion is confirmed, the estate agent can usually release the keys to the buyer.

The seller should leave the property by the time agreed, remove any belongings that are not included in the sale and hand over the keys as arranged. The seller’s conveyancer will use the sale proceeds to repay any mortgage secured against the property and account to the seller for the balance.

The exact timing can depend on the transaction and whether there is a chain, so it is sensible to avoid making assumptions about when the keys will be available.


What happens after completion?

After completion, the buyer’s conveyancer deals with the post completion requirement. These may include submitting a Stamp Duty Land Tax return in England or a Land Transaction Tax return in Wales, where applicable, and applying to HM Land Registry to register the buyer as the new owner and record the lender’s mortgage, if there is one.


How can you help the process run smoothly?

Keep in regular contact with your conveyancer, respond promptly to requests and send money only using the verified bank details provided by your conveyancer. If your circumstances change or you are unsure what to do before exchange or completion, contact your conveyancer as soon as possible.

Exchange and completion are important milestones, but the details can vary between transactions. Your conveyancer can explain what applies to your particular purchase or sale.


Need legal advice? We’re here to help.

If you have questions about your situation or need advice on your next steps, our experienced legal team can help.

Call us on 020 7928 0276 between 9:30am and 6:00pm, or email [email protected].

You can also contact us online by completing our short enquiry form. Tell us a little about your situation and we’ll get back to you as soon as possible.

Not sure which service you need? Get in touch and we’ll help you identify the right team.
author avatar
James Cook

Winning a court case does not always mean receiving your money. If the person ordered to pay fails to do so, you may need to take further steps to enforce the judgment. Where that person owns a property, one option is to apply for a charging order.

But does this mean their home will be sold? And what happens if there is already a mortgage?

A recent High Court decision, Khan v David [2026] EWHC 2554 (KB), provides a useful starting point.

White Namecard for article - Frankie in English

Written by Frankie Ng, Litigation Supervisor


What happened in the case?

Ms Khan was enforcing an American judgment through proceedings in England and Wales. She had obtained an English judgment requiring Mr David to pay approximately US$14.9 million, together with costs.

She applied for a charging order over his interest in a London property. Mr David raised objections, including that the property was his only home and that he had a disability. Another creditor claimed to hold earlier charges over the property.

The court made a final charging order. It explained that the disputed priority of the other creditor’s charges did not prevent that order being made. It also said that the home and disability issues could be considered on any later application for sale.

The court did not order the property to be sold in this judgment. That distinction is central to understanding the process.


What is a charging order?

A charging order secures a court judgment debt against the debtor’s interest in an asset, such as a house or flat. For example, suppose you obtain a judgment requiring someone to pay £30,000. They do not pay, but they own a property. A charging order can attach that debt to their interest in the property.

It does not transfer ownership to you or immediately put cash into your account. It provides security which may help you recover payment from the property.

The order should be protected by the appropriate entry at HM Land Registry. The type of entry depends on the ownership arrangements and the interest charged.


How do you obtain a charging order?

The process normally has two stages.

First, the interim charging order. The creditor applies with details of the judgment, the outstanding amount and the debtor’s interest in the property. The court usually considers the initial application without a hearing.

Second, the final charging order. The application and interim order must be served on the debtor and other relevant people, including any co-owner. They have an opportunity to object. The court then decides whether the charge should continue as a final order. Depending on the procedure and whether objections arise, a hearing may be required.

A final order is not automatic merely because an interim order has been made.


Does a charging order mean the debtor must leave?

No. A charging order alone does not require the debtor to move out or sell the property.

A creditor may retain the security and await a future sale. Alternatively, the creditor may seek an order for sale to enforce the charge.

This requires a separate court claim. The creditor cannot simply instruct an estate agent to sell someone else’s home because a charging order exists.


What is an order for sale?

An order for sale authorises the sale of the property to enforce the charging order.

The creditor must provide supporting evidence, including the outstanding debt, the property’s estimated value, other secured debts and details of people occupying it.

The court must decide whether sale should be ordered. Where a home is involved, the debtor’s circumstances and the interests of other owners or occupiers can be important. An order may include arrangements governing payment, possession and how the sale is conducted.

Obtaining a charging order therefore does not guarantee that the court will subsequently order a sale.


What if the property already has a mortgage?

A property’s value is not the same as the amount available to satisfy your judgment.

Suppose a debtor solely owns a property worth £400,000, with an outstanding mortgage of £350,000. Before sale costs and any other relevant liabilities, the equity is only £50,000.

An earlier mortgage will generally have priority over a later charging order. Sale proceeds must be distributed according to the relevant priorities; the judgment creditor does not automatically get paid first.

Before pursuing a sale, consider the likely proceeds after prior secured debts and costs. A charging order can provide useful security while producing little immediate recovery.


What if the property is jointly owned?

If only one owner owes the judgment debt, the charging order generally attaches to that debtor’s beneficial interest—their financial stake in the property—rather than the other owner’s share.

For instance, a judgment against one spouse does not automatically make the other spouse’s interest available to pay it.

These orders are commonly protected by a restriction at HM Land Registry. A restriction is not equivalent to a mortgage over the whole property, and its effect on a later sale requires careful assessment. Creditors should not assume that every sale will automatically result in payment.


What should creditors and homeowners do?

For creditors, investigate ownership, mortgages and available equity before incurring enforcement costs. The right question is not simply whether the debtor owns a property, but whether this route is likely to recover the money.

For homeowners, do not ignore an interim charging order or a claim for sale. Check the response deadline and provide evidence supporting any objection. A charging order is serious, but it is not an immediate eviction order.

Lisa’s Law’s Litigation and Dispute Resolution team can advise on securing judgment debts, pursuing orders for sale and responding to enforcement against property.


Need legal advice? We’re here to help.

If you have questions about your situation or need advice on your next steps, our experienced legal team can help.

Call us on 020 7928 0276 between 9:30am and 6:00pm, or email [email protected].

You can also contact us online by completing our short enquiry form. Tell us a little about your situation and we’ll get back to you as soon as possible.

Not sure which service you need? Get in touch and we’ll help you identify the right team.
author avatar
James Cook

Buying a property is an exciting moment. You found your dream house, survived the estate agent’s enthusiastic description of the “cosy” second bedroom and are beginning to imagine where the sofa will go. Then you discover a few lines of fine print that could turn into a big problem. That is where restrictive covenants come in.

A restrictive covenant is a legal restriction affecting what you can do with a property. It might prevent you from building an additional property, running a business from home, altering the property in a particular way or carrying out certain types of development.

The good news is that finding a restrictive covenant on the title does not automatically mean that your plans are doomed. The important thing is to understand exactly what the covenant says, whether it affects your property and whether it can be enforced.


Written by Wai Ling Chin, Solicitor


What is a restrictive covenant?

A restrictive covenant is essentially a legal promise not to do something with a property. Common examples include covenants preventing an owner from:

  • building an additional property or extension;
  • using the property for business purposes;
  • altering its external appearance;
  • using it other than as a single private dwelling; or
  • carrying out particular types of development.


Not every covenant found on an old title is automatically enforceable. Whether a particular covenant can be enforced depends on matters including the wording of the covenant, the property concerned and the circumstances in which it was created and subsequently dealt with.


Restrictive covenants and planning permission

Planning permission and restrictive covenants are separate matters. You might obtain planning permission for your extension and still find that a restrictive covenant prevents you from building it.

Planning permission asks: “Will the local planning authority allow this development?”

The covenant asks a rather different question: “Does someone else have a legal right to object to you doing it?”

So you can, unfortunately, get a “yes” from the council and still have a problem with your title. Planning permission does not, by itself, remove or override a private restrictive covenant.


How do I know whether my property is affected?

For registered property, restrictive covenants will often be referred to in the title register. The register may refer to an earlier transfer or conveyance containing the full wording. The precise wording can be critical. For example, “not to use the property for any trade or business” is different from “not to use the property other than as a private dwelling”.

If you intend to work from home, let the property, build an extension or create a separate dwelling, these distinctions may be significant. The title register is therefore an important starting point, but the underlying historic documents may also need to be reviewed.


An eight-point checklist

When assessing a restrictive covenant, consider:

  1. Identify – What does the covenant say and which land does it affect?
  2. Interpret – What does the wording actually mean?
  3. Benefit – Who has the right to enforce it?
  4. Burden – Does it bind the current owner?
  5. Interest – What was the covenant intended to protect?
  6. Scope – Exactly what activity or development is prohibited?
  7. Breach – Would your proposed use or works breach it?
  8. Remedy – Can consent, release, variation, insurance or an application to the Upper Tribunal be considered?


Can a restrictive covenant be removed?

Depending on the circumstances, it may be possible to negotiate a release or variation with the person entitled to enforce the covenant. Alternatively, section 84 of the Law of Property Act 1925 provides a mechanism for applying to the Upper Tribunal (Lands Chamber) for certain restrictive covenants to be discharged or modified, provided the relevant statutory conditions are satisfied.


What happens if I breach a restrictive covenant?

The consequences depend on the circumstances and the nature of the covenant. If an enforceable restrictive covenant is breached, the person entitled to enforce it may be able to seek a remedy through the courts.

Depending on the circumstances, this could include an injunction requiring the breach to stop or, in an appropriate case, damages. This is why it is generally better to investigate the position before carrying out the work rather than discovering afterwards that a neighbour or another person is objecting.


What should you do?

Do not assume that an old covenant is automatically unenforceable. Equally, its presence on the title does not necessarily mean your plans are doomed. If you are buying a property, tell us about your intended plans before exchanging contracts. If you already own the property, review the title before committing substantial sums to building or development works.

In short, a restrictive covenant is not necessarily a reason not to buy a property, but it is something that should be understood before you commit to a purchase or a particular development.


Our Residential Property team are experts in advising on restrictive covenants on property titles. Contact us here.


Need legal advice? We’re here to help.

If you have questions about your situation or need advice on your next steps, our experienced legal team can help.

Call us on 020 7928 0276 between 9:30am and 6:00pm, or email [email protected].

You can also contact us online by completing our short enquiry form. Tell us a little about your situation and we’ll get back to you as soon as possible.

Not sure which service you need? Get in touch and we’ll help you identify the right team.
author avatar
James Cook

The Court of Appeal has reaffirmed the importance of procedural fairness when the Home Office revokes an employer’s sponsor licence. However, its latest decision also shows that identifying an error will not necessarily be enough to have a revocation overturned.

In R (J’s Supermarket Ltd) v Secretary of State for the Home Department; R (Prestige Social Care Services Ltd) v Secretary of State for the Home Department [2026] EWCA Civ 1147, handed down on 4 September 2026, the court considered challenges brought by a supermarket and a care provider whose sponsor licences had been revoked.

Both appeals were dismissed. The judgment offers important guidance on how the Home Office should put allegations to sponsors, how genuine vacancies should be assessed, and when a flawed decision may nevertheless stand.

Namecard for article - Xinru in English

Written by Xinru Jia, Solicitor


Why were the sponsor licences revoked?

The two cases concerned different aspects of sponsor compliance.

For J’s Supermarket, the Home Office identified discrepancies between the roles described in the sponsorship documents and the duties actually performed by two employees. These discrepancies led it to conclude that the sponsored vacancies were not genuine.

Prestige’s case involved concerns about recruitment practices, the suitability of sponsored workers and high staff turnover. The Home Office relied on both a finding that a vacancy was non-genuine and separate failures to comply with sponsorship responsibilities.

The court therefore had to consider two related questions: whether the employers had been given a fair opportunity to respond, and whether the Home Office’s findings justified revocation.


Sponsors must have a fair opportunity to respond

Procedural fairness requires sponsors to understand the substance of the allegations against them and have a meaningful opportunity to answer them before a final decision is made. This is particularly important where the Home Office alleges deliberate wrongdoing.

In J’s Supermarket’s case, the court found that the Home Office had sufficiently identified the discrepancies between the sponsored roles and the employees’ actual duties, as well as its concern that the roles had been created to facilitate immigration permission. The company had been given an opportunity to respond to those concerns.

Prestige’s case illustrated a different problem. The Home Office had withdrawn a concern about whether a vacancy was genuine but later relied on it again without giving the company a further opportunity to respond.

The distinction matters: a sponsor must be able to address the grounds on which the Home Office ultimately relies, including any previously withdrawn allegation that is subsequently revived.


A recruitment failure does not necessarily mean a vacancy is non-genuine

The court also distinguished between the genuineness of a vacancy and the suitability of the person recruited to fill it.

In Prestige’s case, a worker’s inability to drive did not, by itself, rationally establish that the vacancy was non-genuine. A genuine role may exist even where an employer recruits someone who cannot fulfil all of its requirements.

However, that does not make the recruitment failure irrelevant. Inadequate recruitment practices may still support a separate finding that an employer has failed to meet its sponsor duties or lacks the systems needed to comply with them.

Employers must therefore be able to demonstrate both that a sponsored role is genuine and that their recruitment and monitoring processes are effective.


Why did the revocation still stand?

Despite the problems with Prestige’s genuine-vacancy finding, the court dismissed its appeal because other findings independently supported revocation.

Section 31(2A) of the Senior Courts Act 1981 generally requires the court to refuse relief in judicial review proceedings where it is highly likely that the outcome would not have been substantially different without the conduct complained of.

This means that establishing an error and obtaining a remedy are separate questions. A court may identify an unlawful aspect of a decision but still decline to overturn it if the remaining grounds make the same outcome highly likely.

For sponsors considering a challenge, the focus must therefore extend beyond identifying individual errors. It is also necessary to assess whether correcting those errors could materially affect the decision as a whole.


What this means in practice

The judgment highlights the importance of responding fully to a sponsor compliance investigation. Employers should address each allegation, explain any discrepancies clearly and provide supporting evidence. They should also check whether the final decision relies on concerns they were not given a fair opportunity to answer.

Where the Home Office relies on several grounds for revocation, each needs careful consideration. Successfully challenging one finding may not be enough if other grounds remain capable of supporting the decision.

The cases also underline the value of regular compliance reviews. Employers should ensure that workers’ actual duties remain consistent with their sponsored roles and that recruitment, record-keeping and reporting systems work effectively in practice.

There is no statutory right of appeal against sponsor licence revocation. Judicial review may be available, but the prospects of a successful challenge will depend on both the legality of the decision and the significance of any errors identified.

Lisa’s Law works with businesses to apply and maintain sponsor licences, find out more on our Corporate Immigration page here.


Need legal advice? We’re here to help.

If you have questions about your situation or need advice on your next steps, our experienced legal team can help.

Call us on 020 7928 0276 between 9:30am and 6:00pm, or email [email protected].

You can also contact us online by completing our short enquiry form. Tell us a little about your situation and we’ll get back to you as soon as possible.

Not sure which service you need? Get in touch and we’ll help you identify the right team.
author avatar
James Cook

We are delighted to announce that Lisa’s Law Solicitors have retained our Legal 500 status, achieving tier 4 ranking for personal immigration. This is the 3rd year in a row that we have been recognised for personal immigration, and is a testament to the hard work and quality of service provided by our Immigration team led by Mahfuz Ahmed. We have also maintained our accolade for Client Satisfaction: Billing and Efficiency.

This achievement is a source of immense pride for the firm, and demonstrates our dedication to achieving results for our clients. You can view our Legal 500 profile here.


Lisa's Law Legal 500 logo for 2027


Mahfuz Ahmed, Immigration Supervisor:

Namecard for article - Mahfuz Ahmed: Immigration Supervisor

I am proud that we have retained our Legal 500 ranking in immigration. The past year has been difficult on both sides of the practice. Sponsors have had to absorb higher salary and skill thresholds and a run of rule changes. Meanwhile, families have been living with a £29,000 income requirement, a paused rise, and real uncertainty about how long settlement will take and on what terms. Holding our position in that environment is a credit to the team. Clients, whether a business or a family, have needed clear advice delivered quickly, and that is what we have tried to give them.


Lisa’s Law continues to offer expert advice across a range of practice areas including Wills & Probate, Residential and Commercial Conveyancing, Family Law, Litigation, and Business Law. We remain focused on achieving recognition for more practise areas in future Legal 500 editions.


Some recent Immigration Case Studies:

20-Year Residence Appeal Successfully Allowed at Tribunal Hearing

Student Visa Granted in 4 Days: How Lisa’s Law Helped

Domestic Abuse Case: Spouse Visa Holder Granted ILR Under Appendix Victim of Domestic Abuse


Need legal advice? We’re here to help.

If you have questions about your situation or need advice on your next steps, our experienced legal team can help.

Call us on 020 7928 0276 between 9:30am and 6:00pm, or email [email protected].

You can also contact us online by completing our short enquiry form. Tell us a little about your situation and we’ll get back to you as soon as possible.

Not sure which service you need? Get in touch and we’ll help you identify the right team.
author avatar
James Cook

Have a question? Our friendly and experienced team are here to help.

Subscribe to our newsletter

We post weekly articles covering a variety of topics, including immigration, property, and more, so subscribe to our newsletter for the latest updates. 

Subscribe Newsletter Blog Sidebar

This field is for validation purposes and should be left unchanged.
Untitled(Required)