13 London Road,
London, SE1 6JZ
020 7928 0276
[email protected]

News and Insights

Your business has outgrown its premises. You find somewhere better, check the lease and spot a reassuring phrase: six months’ notice. You assume you can give notice, pack up and leave.

That assumption could be expensive. A commercial lease may allow you to leave early only on one particular date. Miss the deadline for exercising that right and you could remain liable for rent for years. But what if you serve notice in time and put the wrong date in the letter? A leading case shows why the answer is more nuanced than you might expect.
White Namecard for article - Frankie in English

Written by Frankie Ng, Litigation Supervisor


Does your lease give you one chance to leave

A break clause gives a landlord or tenant a contractual right to end a lease before its normal expiry. The wording determines when and how that right can be exercised.

For example, a clause allowing a tenant to terminate on the fifth anniversary of the term by giving at least six months’ prior written notice will generally provide a break on that anniversary. It does not ordinarily allow the tenant to leave whenever it chooses after year five simply by giving six months’ notice.

A clause permitting termination at any time after the fifth anniversary on six months’ notice may operate differently. The whole lease must be read carefully, including its definitions and any later variations. Small differences in wording can have substantial financial consequences.

The practical point is to identify both the permitted termination date and the deadline for serving notice. Recording the anniversary in your diary without recording the earlier notice deadline may be too late.


The notice that was one day out

In Mannai Investment Co Ltd v Eagle Star Life Assurance Co Ltd [1997] AC 749, a tenant held two ten-year leases covering office premises and parking in London. Each lease allowed an early break on the third anniversary of the term commencement date, provided the tenant served at least six months’ written notice on the landlord or its solicitors.

The correct break date was 13 January 1995. The tenant served its notices more than six months beforehand and expressly referred to the relevant break clause. However, the notices said that the leases would end on 12 January 1995: one day too early.

The landlord argued that the notices were ineffective. The dispute went all the way to the House of Lords, then the UK’s highest court. By a majority of three to two, the court decided that the notices were valid.


Why the tenant succeeded

The majority considered how a reasonable recipient, knowing the terms of the leases, would understand the notices. In context, it was clear that the tenant was exercising the contractual break right on the permitted anniversary. The incorrect date did not leave a reasonable landlord in doubt about how and when the notices were intended to operate.

This was an objective assessment. The question was not simply what the tenant privately intended, or whether the landlord was willing to overlook a mistake. It was what the notices communicated when read against the relevant background.


A mistake in the letter is different from missing the deadline

Mannai does not give tenants a general right to escape a lease whenever their intentions are clear. The tenant had served its notices in time. The case concerned the meaning of those notices, rather than an extension of the contractual deadline or the creation of a later break date.

If the lease gives only one break opportunity and the tenant misses the notice deadline, sending a notice afterwards will not ordinarily revive that opportunity. Similarly, a clear wish to leave does not dispense with an express requirement about the form or service of the notice, or with other conditions attached to the break.

Those conditions may include payment of specified sums or giving vacant possession. Their effect depends on the wording. A tenant should not assume that moving out, handing over keys or telling the managing agent is enough to end its obligations.


What to check before you serve notice

  • Check the complete lease and any variations. Identify the break date, the notice period and every condition attached to the right.
  • Calculate the service deadline early. Allow for the lease’s service provisions, delivery times and any deemed service rules. Do not assume the date you send the notice is the date it takes effect.
  • Confirm who must receive the notice, at which address and by what method. An email to a familiar contact may not satisfy the lease.
  • Plan for the break conditions. Check payments and possession requirements well before the termination date.
  • Keep evidence of the notice and its service. If a mistake is discovered, obtain advice promptly while there may still be time to act.


If you have already missed the opportunity

Obtain advice before committing to replacement premises or stopping rent payments. Depending on the lease and circumstances, options may include negotiating an agreed early termination with the landlord, known as a surrender, or exploring an assignment to a replacement tenant. Neither should be assumed to release you automatically from all liability.

Landlords receiving an apparently defective notice should also obtain advice before rejecting it. Mannai shows that an incorrect date does not necessarily make a notice invalid.


Need legal advice? We’re here to help.

If you have questions about your situation or need advice on your next steps, our experienced legal team can help.

Call us on 020 7928 0276 between 9:30am and 6:00pm, or email [email protected].

You can also contact us online by completing our short enquiry form. Tell us a little about your situation and we’ll get back to you as soon as possible.

Not sure which service you need? Get in touch and we’ll help you identify the right team.

author avatar
James Cook

In the recent case of IC v AD [2026] EWFC 224, the parties signed a pre-nuptial agreement in January 2012, around seven weeks before their marriage. Its effect was to limit the wife’s claims on divorce, subject to specified provisions for jointly owned property, the family home and certain fund payments.

Namecard for article - Aurora in English

Written by Aurora Chan, Legal Assistant


Under the law in England and Wales, a court can depart from a valid prenuptial agreement if it would be unfair to hold the parties to its terms. Although courts generally give significant weight to properly prepared agreements, they retain discretion to make financial provision where necessary, particularly to meet a party’s reasonable needs.


Background

The relationship broke down after a marriage of approximately 14 years. The husband issued divorce proceedings in May 2024 and moved out of the family home in January 2025.

The parties attempted to resolve their financial arrangements voluntarily, including by exchanging Forms E, but they were unable to agree. The central dispute concerned the interpretation and effect of the pre-nuptial agreement: the husband sought to rely on it, while the wife argued that it should not prevent her from pursuing wider claims.

Both parties were in their early 40s. The husband was a successful private equity professional whose gross annual income exceeded £2.7 million. The wife had spent most of the marriage as a homemaker and caring for the parties’ two children. At the time of the hearing, she was studying for a degree in digital marketing and AI integration. The court found that she was likely to have a modest future earning capacity of around £27,000.

The total asset pool was approximately £26.6 million. Around £8.6 million was readily realisable, while the remaining balance consisted of pensions, deferred interests and other non-realisable assets, including the husband’s shares in his company.


The Legal Position of Nuptial Agreements

Nuptial agreements are not automatically binding in England and Wales. In financial remedy proceedings, the court retains ultimate discretion and must exercise its powers in accordance with section 25 of the Matrimonial Causes Act 1973. The welfare of any minor child of the family is the court’s first consideration. The court must then consider all the circumstances of the case, including:

  1. the parties’ income, earning capacity, property and other financial resources;
  2. their present and foreseeable financial needs, obligations and responsibilities;
  3. the standard of living enjoyed by the family before the breakdown of the marriage;
  4. the age of each party and the duration of the marriage;
  5. any physical or mental disability of either party;
  6. the contributions each party has made, or is likely to make, to the welfare of the family, including caring for the home or family;
  7. conduct, but only where it would be inequitable to disregard it; and
  8. the value of any benefit, such as pension rights, which a party will lose the chance of acquiring because of the divorce.


It is not possible to oust the jurisdiction of the court through any contract or any other agreement.

However, following the Supreme Court’s decision in Radmacher v Granatino, the court should generally give effect to a nuptial agreement where it would be fair to do so with reference to the following factors:

  • whether both parties entered into the agreement freely and with a full appreciation of its implications, which is usually indicated by:
    • each party having received independent legal advice; and
    • full and frank financial disclosure by both parties;
  • whether the agreement was affected by duress, fraud, misrepresentation, undue influence or other unconscionable conduct; and
  • whether, in the circumstances existing at the time of the divorce, it remains fair to hold the parties to the agreement.


None of these circumstances automatically disqualify a nuptial agreement but may diminish the weight which is given to it.

Fairness at the time of divorce remains an essential safeguard. The court may adjust the outcome where necessary to meet needs and to reflect the section 25 factors, even where the agreement was validly made.

The present law on nuptial agreements remains largely based on case law rather than legislation. In 2014, the Law Commission recommended a statutory scheme for “qualifying nuptial agreements”. More recently, the Ministry of Justice’s consultation, A Fairer End to Relationships, sought views on codifying the law and making qualifying nuptial agreements binding where prescribed safeguards are met. The consultation closed on 14 August 2026 and, at the time of writing, the responses were being analysed pending a final report.


The Parties’ Prenuptial Agreement

There was some disagreement between the parties as to the proper interpretation of the prenuptial agreement. The judge observed that its drafting was “sub-optimal”, resulting in some ambiguity as to the parties’ intended arrangements. The court ultimately concluded that the agreement provided that:

  • jointly owned assets would be shared equally;
  • the wife would be entitled to remain in the family home with the children under a Mesher-style arrangement until the youngest child completed tertiary education; and
  • certain investment fund payments would be divided equally.


Save for those provisions, the parties agreed to achieve a clean break, with neither party pursuing financial claims against the other’s remaining assets.

The court was satisfied that the agreement had been properly entered into. Both parties had received independent legal advice, appropriate financial disclosure had been made, and there was no evidence of duress, undue influence or any other factor undermining its validity. Applying the principles in Radmacher v Granatino, the court held that the agreement should be relied upon.


The Judgment

Having concluded that the prenuptial agreement was valid, the court considered whether any circumstances justified a departure from its terms. The wife argued that the agreement produced a highly unequal division of the parties’ wealth and sought a larger award based on the sharing principle. The court rejected that argument but found that a limited departure was justified only to meet the wife’s reasonable financial needs.

In assessing those needs, the court considered the factors set out in section 25 of the Matrimonial Causes Act 1973, in particular the standard of living enjoyed during the marriage, the length of the marriage, their contributions, and their respective financial resources and earning capacity.

Given the husband’s substantial wealth and exceptionally high income, the court adopted a relatively generous assessment of the wife’s needs. It assessed her reasonable expenditure at £13,000 per month, together with £1,000 per month for each child (which were dealt with separately through child maintenance payments). The figures were verified against records of the family’s previous expenditure and the husband’s own budget.

The court then used the Duxbury Tables to calculate the lump sum required to meet the wife’s income needs. Based on an annual income requirement of £156,000 over the remaining 11-year period contemplated by the prenuptial agreement until the youngest child completed tertiary education, the Duxbury calculation produced a capital fund of approximately £1.5 million. Taking into account the wife’s anticipated future earnings and the investment income she could derive from the capital she would receive under the prenuptial agreement, the court exercised its discretion to reduce the spousal maintenance to a lump sum of £1 million.

Under the prenuptial agreement, the wife was entitled to assets valued at £2,837,691. Adding on the £1 million capitalised spousal maintenance award, the wife’s total entitlement equated to a value of £3,837,691.


Conduct

A serious conduct issue also arose during the proceedings. The wife initially denied that any signed prenuptial agreement existed. The judge subsequently found, on the balance of probabilities, that she had removed the original signed agreement from the husband’s study in an attempt to conceal it. Although the court strongly criticised her conduct, it concluded that it did not satisfy the statutory threshold for conduct to affect the financial award, namely that it would be inequitable to disregard it under section 25(2)(g) of the Matrimonial Causes Act 1973. There was also no order as to costs.

The case offers two practical lessons. First, original signed nuptial agreements should be stored securely, and copies should be retained by the parties’ solicitors where appropriate. As nuptial agreements are private documents and are not registered with any public authority, preserving reliable evidence of the executed agreement is essential.

Secondly, the case illustrates the high threshold for conduct to influence the financial outcome. Even serious litigation misconduct will not necessarily affect the court’s substantive award unless it satisfies the high threshold. Regardless, parties should always act in good faith in proceedings. Even if litigation misconduct does not affect the final financial award, it may attract judicial criticism and undermine a party’s credibility or have costs implications.


Key Takeaways

The decision reinforces that, whilst nuptial agreements are not automatically binding in England and Wales, they can carry significant weight. However, even where a nuptial agreement is valid, the court’s ultimate consideration is whether it remains fair to uphold it at the time of the divorce, as the court recognises that circumstances may have changed since the agreement was signed. Events such as the birth of children, ill health, changes in housing needs or significant changes in wealth may give rise to unforeseen needs, justifying a departure from the agreement.

At the same time, the case demonstrates the practical value of a nuptial agreement. Even where the court considers it necessary to depart from the agreement, the departure will generally be limited to what is required to achieve a fair outcome, rather than a complete redivision of the parties’ assets. In this case, although the wife received additional provision, the husband retained the substantial majority of the parties’ wealth because the agreement successfully limited the wife’s claim.

Without the agreement, the wife would likely have been entitled to pursue a much wider sharing claim based on equal division as a starting point. The judgment therefore illustrates both the strength and the limitation of a nuptial agreement. It can provide substantial protection for a party’s wealth, but it cannot exclude the court’s jurisdiction or prevent the court from making limited adjustments where fairness requires.

At the same time, the case also highlights the importance of a carefully drafted nuptial agreement. The parties spent considerable time and expense disputing the interpretation of the agreement because certain parts were unclear. A nuptial agreement should clearly set out the parties’ intentions and anticipate, as far as possible, how its provisions will operate in practice. Ambiguity or poorly considered drafting can give rise to costly litigation. In IC v AD, the parties incurred total legal costs of over £1 million.

It should also be noted that IC v AD was an unusual high-net-worth case involving exceptionally substantial assets and a very high standard of living, far beyond that of the average household. The figures awarded should not be treated as a benchmark for more typical financial remedy cases. Nevertheless, the judgment provides a valuable illustration of the court’s approach to interpreting prenuptial agreements and the principles of needs and fairness.


How we can help

We can advise on nuptial agreements and financial remedy, including:

  • Preparing and review pre-nuptial or post-nuptial agreements, ensuring that procedural safeguards are followed to maximise the weight the agreement is likely to carry;
  • Reviewing or updating an existing agreement where there have been changes in circumstances;
  • Advising on the validity of a nuptial agreement following the breakdown of a relationship;
  • Assisting with the implementation and enforcement of nuptial agreements through consent orders or financial remedy proceedings.


Need legal advice? We’re here to help.

If you have questions about your situation or need advice on your next steps, our experienced legal team can help.

Call us on 020 7928 0276 between 9:30am and 6:00pm, or email [email protected].

You can also contact us online by completing our short enquiry form. Tell us a little about your situation and we’ll get back to you as soon as possible.

Not sure which service you need? Get in touch and we’ll help you identify the right team.
author avatar
James Cook

Home Secretary Shabana Mahmood has confirmed the government’s final plans for how long people will have to wait before they can apply for indefinite leave to remain.

Speaking in the Commons on 2 November 2026, she said settlement will no longer be almost automatic after five years. From now on it will be earned, based on contribution and character. The standard qualifying period for most people is moving from five years to 10 years.

This follows the government’s initial proposals to introduce earned settlement in November 2025, which we covered here.

Namecard for article - Mahfuz Ahmed: Immigration Supervisor

Written by Mahfuz Ahmed, Immigration Supervisor


Key Points in the Announcement 

  • 10-year default ILR route: The standard qualifying period for indefinite leave to remain (ILR) is set to increase from five to ten years for most applicants under the government’s earned settlement plans.
  • Faster settlement routes: High earners and certain highly skilled workers may qualify after three years, while some public service workers, refugees and other eligible groups may qualify after five years.
  • Public funds and benefits restrictions: Applicants will generally need to demonstrate five years without claiming specified public funds before applying for settlement. Those who do not meet this requirement may face a 20-year qualifying period.
  • Care workers and transitional arrangements: Certain care workers who arrived before May 2025 and meet the relevant employment and earnings requirements will retain access to a five-year settlement route. Some others will receive an additional five-year visa period.
  • Longer settlement periods for immigration breaches: Certain immigration breaches and methods of arrival, including arrival by small boat, can result in significantly longer qualifying periods.
  • When will the new ILR rules take effect? The earned settlement proposals are not yet law. The government must introduce the changes through a Statement of Changes to the Immigration Rules. Until then, the existing five-year settlement rules remain in force.


The main routes for ILR are now:

  • Three years: people earning more than £125,000 a year, and those on the highest-skilled routes such as Global Talent and Innovator Founder.
  • Five years: workers earning more than £50,000 a year, certain public service workers (including doctors, nurses and teachers), and refugees who arrived through safe and legal routes.
  • Ten years: the new default for everyone else, including those earning less than £50,000.
  • Longer periods: people who have committed immigration breaches can face waits of 20 years. Those who arrived by small boat face particularly long waits (20 years if working or studying, longer if not).


Benefits and public funds

Anyone who has claimed benefits faces an additional restriction. Those seeking to qualify on the three, five or ten year pathways must not have accessed specified public funds in the five years immediately before they apply for settlement. If they have claimed benefits more recently, or continue to claim, they will instead need to complete 20 years on a qualifying route before they can settle.

There is also a hard requirement that applicants must have no unpaid debt to the taxpayer (including tax, National Insurance or NHS debts). This sits alongside the other mandatory conditions that apply to everyone: a clean criminal record, English to a high standard, and a sustained record of National Insurance contributions.


Care workers

There is a specific transitional arrangement for care workers. Those who joined the Health and Care route (or switched into it) before the Immigration White Paper was published in May 2025, and who have earned at least £25,000 a year in sponsored care work and met their visa conditions, will still be able to apply after five years.

Those who arrived before May 2025 but did not fully meet their visa conditions will be offered a second chance: a further five-year care visa (not tied to their previous employer). They can then apply for settlement at the end of that period. Care workers who arrived after May 2025 fall under the new 10-year default unless they qualify for a faster route.

Similar transitional protection applies to certain lower-paid public sector workers in healthcare and education (such as nursing auxiliaries and teaching assistants) who were already here before May 2025.


Our comments

The big shift is the move to a 10-year default for most people already in the UK. The rules that will apply are those in force when a settlement decision is made, not when the person first arrived. That means many people who came expecting to settle after five years will now face a longer wait.

The three-year and five-year routes for higher earners and certain public service workers are useful, but the thresholds are high. For most clients on standard Skilled Worker visas, the realistic planning assumption is now 10 years unless they can show they fall into one of the accelerated categories.

The benefits rule is significant. Even people who would otherwise qualify on a three-, five- or ten-year route will need five continuous years without claiming specified public funds before they can apply. Those who have claimed more recently will be pushed to the 20-year route. Combined with the requirement of no unpaid debt to the taxpayer, this will catch some people who have not previously focused on their benefits history.

The care worker announcement is welcome for those who arrived before May 2025 and have been working and earning at the required level. It does not protect everyone on the route, and it does not help those who arrived later. Anyone in that group will still need to meet the general character requirements, including the benefits condition.

None of this is law yet. The policy still needs to be set out in a Statement of Changes to the Immigration Rules. Until that happens, the current five-year rules remain in force. Anyone approaching the five-year mark should check their position carefully, including any history of claiming public funds and keep an eye on the rules changes when they are published.

Contact Lisa’s Law here to get help with settlement, or find out more about our work visa services here.


Need legal advice? We’re here to help.

If you have questions about your situation or need advice on your next steps, our experienced legal team can help.

Call us on 020 7928 0276 between 9:30am and 6:00pm, or email [email protected].

You can also contact us online by completing our short enquiry form. Tell us a little about your situation and we’ll get back to you as soon as possible.

Not sure which service you need? Get in touch and we’ll help you identify the right team.
author avatar
James Cook

Owning valuable property or having substantial wealth does not, in itself, mean that a person has done anything unlawful. However, where the authorities have grounds to question how particular assets were acquired, English law provides an investigative procedure that can require an explanation of their origin – even when no criminal charge has been brought.

On 23 October 2026, the Crown Prosecution Service (“CPS”) announced that the High Court had granted an Unexplained Wealth Order (“UWO”) and an Interim Freezing Order (“IFO”) against two British nationals and companies associated with them. Assets worth approximately £50 million are affected.

The announcement is a useful reminder that asset recovery investigations are not limited to criminal prosecutions. It also raises practical questions for individuals, property owners and companies: when can a UWO be made, what information must be produced, and does an order mean that assets have already been confiscated?

Peggy Lim article namecard

Written by Peggy Lim, Solicitor


What happened in this case?

According to the CPS, the assets include a yacht valued at approximately £1.9 million, around £2.6 million held in a bank account, eight vehicles worth approximately £600,000, and properties situated in England, France, Spain and Portugal. The CPS described the case as part of its investigation into suspected laundering of international illicit funds in the United Kingdom.

The two individuals have been identified publicly only as Mr X and Ms X. The CPS said that an application concerning their anonymity was expected to be heard by the High Court. As at the announcement on 23 October 2026, neither individual had been charged with or convicted of a criminal offence.

The Court has given the respondents and associated companies three months to account for the funds used to acquire the relevant assets. The CPS has not published a full judgment or the detailed evidence relied upon to obtain the orders. It would therefore be inappropriate to assume that the underlying allegations have been proved.


What is an Unexplained Wealth Order?

A UWO is an investigative order made by the High Court under sections 362A and following of the Proceeds of Crime Act 2002 (“POCA 2002”). The regime was introduced by the Criminal Finances Act 2017 and came into operation in England and Wales in January 2018. It was subsequently amended by the Economic Crime (Transparency and Enforcement) Act 2022.

In broad terms, a UWO requires a respondent to explain their interest in specified property and how the property was obtained. The order may require information and supporting documents concerning the purchase, ownership or funding of the asset.

It is important to distinguish the source of funds used for a particular purchase from the wider source of a person’s wealth. For example, a property may have been purchased through a company or with money received as a gift, loan, inheritance or business distribution. An explanation may need to trace the relevant transactions and identify the persons and entities involved, rather than merely stating that the owner has substantial assets.


When can the High Court make a Unexplained Wealth Order?

Section 362B POCA 2002 imposes specific statutory conditions. Among other matters, the Court must have reasonable cause to believe that the respondent holds property worth more than £50,000. Where several items of property are concerned, their value may be considered together.

The Court must also be satisfied that there are reasonable grounds for suspecting either that the respondent’s known lawfully obtained income would have been insufficient to acquire the property, or that the property was obtained through unlawful conduct.

In addition, the respondent must fall within the relevant category: a politically exposed person as defined in the legislation, or a person whom there are reasonable grounds to suspect is or has been involved in serious crime, or is connected to someone so involved.

These are substantive requirements. The mere fact that someone owns an expensive house, holds assets overseas, has a complex corporate structure or is a foreign national is not, by itself, enough to satisfy the statutory test. The published CPS announcement does not identify which of the statutory routes was relied upon in this particular application.


What is the difference between a Unexplained Wealth Order and a freezing order?

The two orders perform different functions. A UWO seeks information. An IFO, available under section 362J POCA 2002, prevents dealings with the relevant property where the Court considers that freezing is necessary to avoid frustrating a possible future recovery order.

Depending on the terms of an IFO, a respondent or another person with an interest in the property may be prohibited from selling, transferring or otherwise dealing with it, subject to any permitted exclusions or subsequent variation.

A freezing order does not transfer ownership to the Government, and a UWO is not a final finding that property represents criminal proceeds. The CPS must pursue separate civil recovery proceedings if it seeks permanent recovery. For assets located outside the United Kingdom, any practical enforcement may also involve overseas legal procedures or cooperation.


Does the CPS need to obtain a criminal conviction first?

No. A UWO is a civil investigative measure. It can be sought before any criminal prosecution and does not depend on a prior conviction. The CPS announcement makes clear that the two respondents in this case had not been charged or convicted.

Civil recovery is also distinct from criminal confiscation following conviction. Under Part 5 POCA 2002, the authorities may seek the recovery of property obtained through unlawful conduct through civil proceedings. The civil standard of proof, rather than the criminal standard, applies. That does not mean that an application for a UWO automatically leads to a recovery order.


What happens if the recipient responds, or does not respond?

A respondent must consider the actual terms of the UWO, the questions asked, the documents required and the deadline fixed by the Court. The three-month period reported in this case is case-specific; it should not be treated as the response period for every UWO.

Under section 362C POCA 2002, failure to comply without reasonable excuse can create a rebuttable presumption, for subsequent Part 5 civil recovery proceedings, that the relevant property is recoverable property. The statutory presumption is subject to conditions, including those concerning the value of the respondent’s interest. Importantly, non-compliance does not itself result in automatic confiscation.

If a respondent complies, or purports to comply, section 362D applies instead. The authorities can still examine the information supplied and decide whether further investigation or civil recovery proceedings are appropriate. Responding does not guarantee that a freezing order will immediately be discharged.

Accuracy is particularly important. Section 362E makes it a criminal offence knowingly or recklessly to provide a materially false or misleading statement in purported compliance with a UWO. Anyone served with an order should therefore obtain legal advice promptly and avoid speculative or incomplete explanations presented as established fact.


Can a Unexplained Wealth Order involve companies, trusts and overseas assets?

Yes. Ownership arrangements may be more complex than the name shown on a title register. The statutory concept of holding property can extend to effective control, trust arrangements and corporate ownership. Amendments made in 2022 also enable specified responsible officers of corporate respondents to be required to provide information.

A structure involving a UK company, an overseas company, a trust or several layers of ownership is not inherently unlawful. However, it may make it necessary to identify beneficial owners, directors, sources of funding, transfers between connected parties and the commercial purpose of the transactions.

The involvement of properties in France, Spain and Portugal in the CPS announcement also illustrates the possible international scope of an investigation. It does not mean that a UK court order can always be enforced abroad without the assistance of the relevant jurisdiction.


What should property owners and businesses do?

The practical lesson is to preserve a clear and consistent documentary explanation of significant acquisitions and transfers. This is especially relevant where property has been purchased through a company, with funds originating abroad, or using gifts, loans or distributions from connected parties.

Useful documents may include purchase contracts and completion statements, bank statements showing the payment trail, mortgage or loan agreements, records of employment or business income, tax records, inheritance or gift documents, company accounts, shareholder and director records, and documents identifying beneficial ownership.

The evidence should tell a coherent story: where the money originated, how it moved, why it was paid, who controlled it, and how it was ultimately used to acquire the asset. A document showing the immediate bank transfer may not be enough if the underlying origin of the money remains unexplained.

Where a UWO or IFO has actually been served, deadlines and restrictions must be treated seriously. An affected person may need advice on the scope of the order, possible applications to vary or discharge it, permitted expenditure and the preparation of an accurate response. The appropriate steps will depend on the wording of the order and the evidence.


How can we help?

We can advise individuals, property owners and businesses on the legal implications of unexplained wealth investigations, questions concerning the source of funds and source of wealth, and the documentation needed to explain substantial acquisitions or complex ownership structures.

Where a UWO or freezing order has been made, we can review the order, consider the available legal and procedural options and assist with the preparation of a response, including working with specialist counsel and other advisers where required.

Early advice can help ensure that relevant records are preserved, inconsistencies are identified and the response properly addresses the matters raised by the authorities.


Final thoughts

The significance of the CPS announcement is not that possession of £50 million in assets proves wrongdoing. It does not. Nor has the High Court, by making a UWO and an interim freezing order, finally determined that these assets should be forfeited.

The lesson is that substantial or complex holdings may face close scrutiny where the statutory conditions are met. Individuals and companies should be able to explain not only what they own, but how the assets were funded – and support that explanation with reliable records.


Need legal advice? We’re here to help.

If you have questions about your situation or need advice on your next steps, our experienced legal team can help.

Call us on 020 7928 0276 between 9:30am and 6:00pm, or email [email protected].

You can also contact us online by completing our short enquiry form. Tell us a little about your situation and we’ll get back to you as soon as possible.

Not sure which service you need? Get in touch and we’ll help you identify the right team.
author avatar
James Cook

When selling a business, such as a restaurant, takeaway, hair salon or retail shop, the seller may also need to transfer their existing commercial lease to the buyer. This is known as an assignment of lease.

However, selling a business does not automatically mean that the buyer can take over the premises. Most commercial leases contain restrictions on assignment, which means that the tenant may need to obtain the landlord’s consent before transferring the lease to the buyer.

This is an important part of the transaction, as failure to obtain the necessary consent could delay the sale or result in a breach of the lease.

Namecard for article - Emily Ding in English 1

Written by Emily Ding, Trainee Solicitor


Why Do You Need Landlord’s Consent?

Most commercial leases require the tenant to obtain the landlord’s written consent before assigning the lease. This is usually dealt with by a legal document known as a Licence to Assign.

The landlord will want to make sure that the incoming tenant is suitable and financially capable of taking over the lease obligations.

The landlord may therefore request certain documents from the buyer, such as bank statements, accountant’s references, previous landlord’s references or business information.

Under the Landlord and Tenant Act 1988, where applicable, the landlord must deal with a written application for consent within a reasonable time and must not unreasonably withhold consent.

However, the landlord may have reasonable grounds to refuse consent, for example, where there are genuine concerns about the buyer’s financial ability to pay the rent.


Will The Seller Still Be Liable After Selling the Business?

This is something that many business owners may overlook.

In some cases, the landlord may require the outgoing tenant to enter into an Authorised Guarantee Agreement (AGA) as a condition of granting consent.

This means that even after selling the business, the outgoing tenant may remain liable if the incoming tenant fails to comply with the lease obligations, such as paying rent.

The outgoing tenant should therefore carefully consider the terms of the AGA before agreeing to it.


What Should Sellers Consider?

Obtaining landlord’s consent can take time, particularly where financial references, a rent deposit or an AGA are required.

It is therefore advisable to review the lease and apply for consent as early as possible. The business sale and lease assignment should also be properly coordinated to ensure that the buyer has the legal right to occupy the premises upon completion.


Conclusion

Selling a business does not automatically give the buyer the right to take over the existing commercial lease. Landlord’s consent may be required, and additional conditions may apply.

Seeking legal advice at an early stage can help both parties understand their obligations and avoid unnecessary delays to the transaction.


Need legal advice? We’re here to help.

If you have questions about your situation or need advice on your next steps, our experienced legal team can help.

Call us on 020 7928 0276 between 9:30am and 6:00pm, or email [email protected].

You can also contact us online by completing our short enquiry form. Tell us a little about your situation and we’ll get back to you as soon as possible.

Not sure which service you need? Get in touch and we’ll help you identify the right team.
author avatar
James Cook

Yesterday’s Budget contained a handful of immigration announcements aimed at making it easier for UK businesses to attract and keep highly skilled people. The government says it wants “the most pro-business migration system in Europe for highly skilled workers”. The main points are as follows.

Namecard for article - Mahfuz Ahmed: Immigration Supervisor

Written by Mahfuz Ahmed, Immigration Supervisor


Salary thresholds for Skilled Workers

From spring 2027 the occupation-specific salary floors will drop from the median to the 25th percentile. The general threshold will still go up in line with 2026 wage data and then be updated every year. The various new entrant discounts will be simplified into one figure, and the PhD discount will go. In short, some skilled worker visa roles should become slightly easier to sponsor, but the overall salary bar is still rising.


More time to find a new job

From 2027 the highest-skilled sponsored workers will get up to six months to find another sponsor if their job ends. That is longer than the current curtailment period and should help people who are already well established here.


High Potential Individual visa

The HPI route is being widened to the top 150 global universities, with a matching increase in the annual cap. It remains an unsponsored route for recent graduates.


Graduate visa

Graduates from “high-compliance” universities that show strong labour market outcomes will still get two years on the Graduate visa. Everyone else will see the length cut to 18 months from January 2027. We do not yet know exactly which universities will qualify.


Sponsorship costs no longer a benefit in kind

If an employer pays the Immigration Skills Charge or a Certificate of Sponsorship fee, that payment will not be treated as a taxable benefit for the worker. This removes a small but annoying tax uncertainty for sponsors.

There was nothing on a new investor route and nothing further on the Home Office’s earned settlement plans.


Our comments

These are steps in the right direction for employers who rely on skilled international staff, but they are not significant changes. The salary threshold changes will help some occupations more than others, and the overall cost of sponsorship remains high. The longer curtailment period is useful for senior people, though we will need to see the exact criteria before we can advise clients.

For universities and students, the two-year Graduate visa is only being kept for a select group. Anyone graduating next year should check early whether their institution is likely to qualify.

As usual, the real detail will come in the Immigration Rules and guidance later. Until then, sponsors and applicants should carry on planning on the basis of the current rules and treat these announcements as signals of direction rather than immediate changes. We will update clients as soon as the further detail is published.


Need legal advice? We’re here to help.

If you have questions about your situation or need advice on your next steps, our experienced legal team can help.

Call us on 020 7928 0276 between 9:30am and 6:00pm, or email [email protected].

You can also contact us online by completing our short enquiry form. Tell us a little about your situation and we’ll get back to you as soon as possible.

Not sure which service you need? Get in touch and we’ll help you identify the right team.
author avatar
James Cook

When someone dies abroad leaving money, shares or a property in England and Wales, the grant of probate issued where they lived is often not enough on its own. UK banks and share registrars usually want to see an English grant, and HM Land Registry will not deal with property here without one. That is because a grant only gives authority in the country whose court issued it.

For some countries, you can ask the Probate Registry to reseal the grant you already have, instead of applying for a new English grant. That avoids a completely new application, but only certain countries’ grants qualify, and UK inheritance tax has to be dealt with first.

Namecard for article - Yi Ling English

Written by Yi Ling Lio, Private Client Paralegal


What does resealing a grant of probate mean?

The Probate Registry stamps the foreign grant with the seal of the Family Division of the High Court. From then on, it works in England and Wales as if a court here had made it. For example, the deceased may have lived in Hong Kong and had an account with a UK bank. Once the Hong Kong grant is resealed, the executor named in it can close that account, sell or transfer property, and deal with shares in the usual way.


Which countries’ grants can be resealed in England and Wales?

Resealing is only possible for grants from countries and territories covered by the Colonial Probates Acts 1892 and 1927. Most are current or former Commonwealth countries, including Hong Kong, Malaysia, Singapore, Australia, New Zealand, Canada and Kenya. South African grants can also be resealed, although South Africa is not on the list itself. You will find the full list at the end of this article.

In Australia and Canada, the list goes state by state or province by province, so every Australian state is covered but Quebec is not. No US state is on the list. Jersey, Guernsey and the Isle of Man are not on it either.

Grants from Scotland and Northern Ireland do not need resealing at all. As long as the grant notes that the person died domiciled there, it is recognised in England and Wales as it is.


What if the country is not on the list?

Grants from mainland China, Taiwan, India, the United States and most of Europe cannot be resealed. If the grant came from one of those countries, you will need to apply for a new grant in England and Wales.

Where the person died domiciled abroad, the English grant can go to one of three people:

  • the person put in charge of the estate by the court in the country of domicile
  • the person entitled to the estate under that country’s law
  • the executor named in the will, if the will is in English or Welsh


Depending on which of these applies, the registry may have to make an order first, and you may need evidence of the foreign law from a lawyer qualified in that country. All of this takes longer than a reseal, so check the list before you start.


Who can apply to reseal a grant?

The application is made by the person named on the foreign grant, or by someone they have authorised in writing. Executors living abroad often ask a solicitor here to apply for them, under a letter of authority or a power of attorney.

Unless a registrar agrees otherwise, the grant must have been made to one of the same three people listed above. That brings in domicile, which is a legal concept and not the same as nationality or where someone happened to be living. If there is any doubt about it, the registry may ask for evidence. Our article on Matyas v Daniel shows how closely the courts look at this.

If the grant was made to more than one person, the registry may ask about anyone who is not joining in the application, and a grant made to more than four people cannot be resealed. A grant that is limited, or only lasts for a set period, needs a registrar’s permission. And even where the country is on the list, the registrar can refuse a reseal and tell you to apply for a new English grant instead.


Inheritance tax comes first

The registry will not reseal a grant until UK inheritance tax has been reported and any tax due has been paid. This is usually the part that takes longest.

Which form you need depends on the person’s connection with the UK and what they owned here. For deaths on or after 6 April 2025, the test is long-term UK residence, which broadly means being UK resident for at least 10 of the previous 20 tax years. For earlier deaths, the test is domicile. If the person was neither, they are generally taxed only on what they owned in the UK, and that can still mean tax to pay.


IHT207, the short form. You can use this instead of a full account if all of the following apply:

  • the person was not a long-term UK resident when they died (or, for deaths before 6 April 2025, was domiciled abroad)
  • they had never been UK domiciled, deemed domiciled or long-term UK resident
  • their UK assets were only cash and quoted shares, worth no more than £150,000 in total before debts
  • they had not given away more than £3,000 a year of UK assets in the seven years before they died
  • they did not hold an indirect interest in UK residential property, such as a UK home owned through a company


IHT400, the full account. Any other estate needs a full IHT400 sent to HMRC. That includes an estate with UK property, such as a London flat, or shares in a private company, even if the estate is below the tax threshold and nothing is payable. Once HMRC has processed the IHT400, it sends a letter with a probate code and the estate figures. The registry needs that code before it will look at the application. (The code replaced the old IHT421 form in January 2024.)

Deadlines. Any inheritance tax is due by the end of the sixth month after the month of death. After that, HMRC charges interest, even if the executors cannot yet access the estate’s money. The IHT400 must be filed within 12 months of the end of the month of death, and filing late can lead to penalties. So in an estate that owes tax, the payment deadline often arrives before the reseal does.

Tax on UK property can usually be paid in ten yearly instalments, so the full amount is not due at once. Many UK banks and building societies will also pay inheritance tax straight to HMRC from the deceased’s own accounts before any grant is issued, under HMRC’s Direct Payment Scheme.


What documents do you need?

The reseal application is made on paper, not online. You will usually need:

  • the foreign grant: the original, a duplicate sealed by the court that issued it, a copy certified by that court, or an exemplification
  • the will, if the grant does not already include a copy, certified by the court that issued the grant, plus plain copies of both the grant and the will
  • form PA1P if there is a will, or PA1A if there is not
  • the IHT207, or HMRC’s letter with the probate code if you sent an IHT400
  • the letter of authority or power of attorney, if someone is applying on the grantee’s behalf
  • an English translation of the will, if it is not in English
  • the court fee


What if the grant or will is not in English?

Only grants issued in English, or in English alongside another language, can be resealed. If the grant is only in another language, resealing is not available and you will need to apply for a new grant in England and Wales.

A will that is not in English needs an English translation. The registry accepts a translation by an English notary under seal, or by a British consular official. A translation by anyone else, however fluent, is only acceptable if a district judge or registrar gives directions first.


How long does it take and what does it cost?

The registry fee is £526 if the estate in England and Wales is worth more than £5,000. It went up from £300 in July 2026. If the estate is £5,000 or less, there is no fee.

Extra sealed copies cost £2 each if you order them with the application, or £16 each if you order them later. Each bank or share registrar will usually want its own copy, so decide how many you need before you apply.

Most of the waiting is on the tax side, because HMRC has to process any IHT400 before the registry will look at the papers. Once that is done, allow around four to five months for the reseal itself. When the registry is satisfied, it reseals the grant, sends it back to you and tells the court abroad.

A reseal is not always quicker, though. The registry can be slower with reseals than with new English grants, and some banks see them less often and come back with more questions. For some estates, a new English grant ends up being the easier route. Take advice on which route suits the estate.


In summary

If someone has died abroad leaving assets here, two questions decide the route. Did the grant come from a country on the list, and is it in English? If both answers are yes, a reseal may work. If not, you will need a new English grant, and it is better to know that early.

Either way, inheritance tax comes first. The HMRC deadlines run from the month of death, whether or not your paperwork is ready.


How we can help

We act for executors abroad who need to deal with UK assets. We can check whether the grant can be resealed, deal with HMRC and the Probate Registry, and work alongside your lawyer abroad, in English, Mandarin or Cantonese. If there is UK property in the estate, get in touch early.


The list is in Schedule 1 to the Colonial Probates Act Application Order 1965, which still uses many old colonial names. Using today’s names, it includes:

  • Asia: Hong Kong (still covered after the 1997 handover), Malaysia, Singapore, Brunei and Sri Lanka
  • Australia and New Zealand: New Zealand, and in Australia all six states (New South Wales, Queensland, South Australia, Tasmania, Victoria and Western Australia), the Australian Capital Territory, the Northern Territory, Christmas Island, the Cocos (Keeling) Islands and Norfolk Island
  • Canada: Alberta, British Columbia, Manitoba, New Brunswick, Newfoundland and Labrador, Nova Scotia, Ontario, Prince Edward Island, Saskatchewan and the Northwest Territories
  • Africa: Botswana, Eswatini (Swaziland), The Gambia, Ghana, Kenya, Lesotho, Malawi, Nigeria, Seychelles, Sierra Leone, Tanzania, Uganda, Zambia and Zimbabwe
  • The Caribbean and Atlantic: Anguilla, Antigua, the Bahamas, Barbados, Belize, Bermuda, the British Virgin Islands, the Cayman Islands, Dominica, the Falkland Islands, Grenada, Guyana, Jamaica, Montserrat, St Helena, St Kitts and Nevis, St Lucia, St Vincent, Trinidad and Tobago, and the Turks and Caicos Islands
  • The Pacific: Fiji, Kiribati, Papua New Guinea, the Solomon Islands and Tuvalu
  • Europe and elsewhere: Gibraltar, the Republic of Cyprus, the British Sovereign Base Areas in Cyprus, and the British Antarctic Territory (grants from the Turkish Republic of Northern Cyprus cannot be resealed)


South Africa is not on the list, but South African grants can still be resealed.


Need legal advice? We’re here to help.

If you have questions about your situation or need advice on your next steps, our experienced legal team can help.

Call us on 020 7928 0276 between 9:30am and 6:00pm, or email [email protected].

You can also contact us online by completing our short enquiry form. Tell us a little about your situation and we’ll get back to you as soon as possible.

Not sure which service you need? Get in touch and we’ll help you identify the right team.

author avatar
James Cook

You have been told by the police to attend a custody suite. Perhaps the investigation has been continuing for some time and the police now want to deal with the allegation formally. The word “custody” immediately raises an obvious concern: if you go in, are you going to be allowed to go home?

Attending a custody suite does not itself mean that you will automatically be kept there. Depending on what happens, you may be charged and released, released subject to bail conditions, or kept in custody for a court appearance. The immediate question is therefore not only what you are accused of, but also what information is available to show why you should be allowed to leave on bail.

White Namecard for article - Paul Cheuk in English (1)

Written by Paul Cheuk, Solicitor


Speak to a Solicitor Before You Attend

If the police ask you to attend a custody suite, we suggest obtaining legal advice immediately rather than waiting until you arrive. A person detained at a police station has the right to consult a solicitor privately, and free independent legal advice is available at the police station.

A solicitor can help to establish what the police intend to do and advise you about the likely procedure. More importantly, the solicitor can start thinking about matters which you may not yet have considered, including whether bail is likely to become an issue and what information should be available to address it.

There is an important practical advantage in speaking to the solicitor before attendance. It gives time to prepare rather than trying to obtain addresses, employment documents or other information after the client is already inside the police station.


The Police Know the Allegation Better Than They Know You

By this stage, the police may know a great deal about the alleged offence. They may have statements, messages, CCTV or other material collected during the investigation. What the custody officer may know much less about is your personal life.

When someone is about to be charged, almost all of their attention naturally goes to the allegation. They are thinking about what happened, what the witnesses have said, what messages exist and how the allegation can ultimately be defended.

Those issues are important, but they may not be the first issue that needs to be dealt with that afternoon. Before any trial takes place, somebody may first have to decide whether you are going home.

Do you have a permanent home in the UK? How long have you lived there? Do you have stable employment? Does your spouse or your children live here? Do you operate a business? Do you care for somebody? Have you attended voluntarily whenever the police asked you to do so?

These matters can be important when considering whether there is any genuine reason to believe that you would disappear, fail to attend court, commit another offence or interfere with the case. If bail has not been considered in advance, one may suddenly find themselves trying to remember an employer’s details, explain where they live, identify evidence of their family circumstances while already inside a custody suite without the help of the phone or internet.


Your Address Can Become Material

Something as ordinary as where you live can suddenly become highly relevant. A person who has lived at the same address for many years may be able to demonstrate a strong connection with the area. If someone has no settled address, or their living arrangements are unclear, the police may have more questions about where that person will be if released.

Depending on the circumstances, it would be helpful to have simple evidence available. This could include a tenancy agreement, council tax bill, mortgage statement or other document showing where the client actually lives.

It is not a question of arriving with a suitcase full of paperwork. The useful documents will depend on the particular concern which might arise.


Work and Family Can Help Show Your Connection to the UK

Employment may also be important. Someone with permanent employment, a business, professional responsibilities or regular working commitments in this country may have obvious reasons to remain here and attend court.

Family circumstances can also form part of the picture. A person whose spouse, children and home are all in the UK may be able to demonstrate substantial connections with this country.

Again, the evidence may be straightforward. A recent payslip, employment contract, company record or evidence of family responsibilities may sometimes be useful.

It is much easier to produce that material if somebody has thought about it before the client attends the police station.


What If You Have Connections Overseas?

Having family, nationality, property or business interests overseas does not mean that bail will automatically be refused. Many people living in the UK naturally have significant connections with other countries.

However, if the police are concerned that someone may leave the country rather than attend court, overseas connections may become relevant.

The complete picture therefore matters. How long have you lived in the UK? Where is your main home? Where do you work? Where does your immediate family live? Have you complied with previous police requests? Have you previously travelled while under investigation and returned when required?

Where foreign travel is the particular concern, surrendering a passport may sometimes be considered as a bail condition. The important question is whether a practical condition can address the perceived risk rather than whether detention is necessary simply because the client has an overseas connection.


Prepare Before You Walk Through the Door

When a client tells us that the police have asked them to attend a custody suite, our work should begin before the attendance itself.

We want to understand what the police intend to do, advise the client about the process, consider the allegation and prepare for any interview. We also want to know where the client lives, what they do for work, what family responsibilities they have, how strong their connections are with the UK, whether there are significant overseas connections and whether they have previously complied with police or court requirements.

At Lisa’s Law, when assisting clients who are asked to attend a police station or custody suite, we do not wait for the bail question to arise before thinking about it. Defending the allegation is important, but so is the immediate question of liberty. Preparing for both before attending can make a significant practical difference.


Need legal advice? We’re here to help.

If you have questions about your situation or need advice on your next steps, our experienced legal team can help.

Call us on 020 7928 0276 between 9:30am and 6:00pm, or email [email protected].

You can also contact us online by completing our short enquiry form. Tell us a little about your situation and we’ll get back to you as soon as possible.

Not sure which service you need? Get in touch and we’ll help you identify the right team.
author avatar
James Cook

Buying a home is a major commitment, and circumstances can change during the conveyancing process. A survey may reveal unexpected problems, mortgage funding may fall through, or the buyer may reconsider.

In England and Wales, the consequences largely depend on whether contracts have been exchanged.

Before exchange, withdrawing usually means losing money already spent. After exchange, it can lead to substantial financial liability.

Namecard for article - John in English 1

Written by John Ju, Conveyancing Paralegal

Before Exchange: Generally Free to Withdraw

Before exchange of contracts, an accepted offer is usually “subject to contract”. Neither party is legally committed to completing the transaction. A buyer can generally withdraw without compensating the seller simply for changing their mind. The seller can also withdraw or accept another offer.

However, withdrawing is unlikely to be cost-free. The buyer may have already paid for searches, a survey, mortgage arrangements and legal work. Whether any fees are refundable depends on the provider’s terms and the work completed.

The seller may also incur wasted expenses and delays, particularly where the withdrawal disrupts a chain. In an ordinary transaction, these losses do not automatically become the buyer’s responsibility before exchange.

Separate agreements may change the position. A reservation or exclusivity agreement, for example, may impose payment obligations or limit refunds. Buyers should obtain legal advice before entering into such agreements and check the terms before withdrawing.

After Exchange: A Binding Commitment

Exchange of contracts creates a legally binding agreement to buy and sell the property. Both parties commit to the contract terms, including the completion date. There is generally no cooling-off period, and changing your mind does not release you from your obligations.

A buyer who withdraws without a valid legal or contractual basis risks losing their exchange deposit, commonly 10% of the purchase price. On a £400,000 purchase, this could mean £40,000. Depending on the contract conditions, paying a smaller deposit does not necessarily limit liability to the amount paid.

The financial consequences may extend beyond the deposit. The seller may claim compensation for recoverable losses caused by the breach, potentially including a

shortfall if the property is subsequently sold for less. Any claim must be supported by evidence and assessed under the contract and applicable law.

If completion is delayed, contractual interest may also become payable. The seller may serve a notice to complete, setting a final deadline for completion. Under the Standard Conditions of Sale, this is normally ten working days, excluding the day the notice is given. Failure to comply may allow the seller to terminate the contract, retain the deposit and pursue damages.

What Should a Buyer Do If a Seller Pulls Out?

Before exchange, a seller can generally withdraw without compensating the buyer for costs already incurred. If this happens, contact your conveyancer and estate agent to confirm the seller’s position and establish whether the transaction can still proceed. Your conveyancer can also check whether any separate reservation or exclusivity agreement gives you rights or remedies.

After exchange, the seller is legally bound by the contract and cannot simply withdraw because they have changed their mind. Contact your conveyancer immediately if the seller refuses or fails to complete. Depending on the circumstances and the contract terms, your options may include agreeing a revised completion date, serving a notice to complete or pursuing legal remedies.

If the seller fails to comply with a valid notice to complete, you may be entitled to terminate the contract, recover your deposit and claim damages for recoverable losses. In some cases, it may also be possible to seek a court order requiring the seller to complete the sale. Your conveyancer can advise on the appropriate steps before you agree to any cancellation or commit to another purchase.

What Should a Seller Do If a Buyer Pulls Out?

A buyer pulling out can be stressful, particularly if you are relying on the sale to fund your next purchase. Your first step should be to contact your conveyancer and establish whether contracts have been exchanged, as this determines your rights and the options available.

Before exchange, ask your estate agent to confirm why the buyer has withdrawn and whether the problem can realistically be resolved. If the purchase will not proceed, discuss putting the property back on the market and contacting other interested buyers. Tell your conveyancer promptly if the withdrawal affects a related purchase, so they can review your commitments and help you manage the impact on the chain. Although you may have incurred wasted costs, these are not ordinarily recoverable from the buyer unless a separate agreement provides otherwise.

After exchange, seek legal advice before agreeing to cancel the sale, returning any deposit or committing to sell to someone else. Your conveyancer can assess whether the buyer has a valid basis for withdrawing and advise on the appropriate response, which may include negotiating a short extension, serving a notice to complete or pursuing contractual remedies.

Keep copies of relevant correspondence and records of any additional expenses or losses. If the contract is lawfully terminated and you seek compensation, you will generally need to take reasonable steps to limit your losses, such as remarketing the property promptly. Any claim should reflect recoverable losses and account for any deposit retained.

If you need advice or assistance, please contact us here. Our team will be happy to help.

Need legal advice? We’re here to help.

If you have questions about your situation or need advice on your next steps, our experienced legal team can help.

Call us on 020 7928 0276 between 9:30am and 6:00pm, or email [email protected].

You can also contact us online by completing our short enquiry form. Tell us a little about your situation and we’ll get back to you as soon as possible.

Not sure which service you need? Get in touch and we’ll help you identify the right team.
author avatar
James Cook

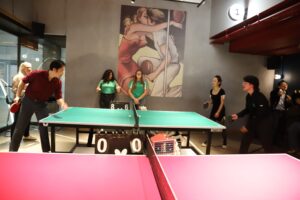
Lisa’s Law staff and business partners alike recently gathered on Friday 16 October for our Autumn Social at Bounce in the impressive Battersea Power Station, for an evening of food, drinks, networking and friendly competition.

Coming together outside of work is an important part of life at Lisa’s Law. With office-based and remote colleagues across several departments, events like this give us the chance to reconnect and build relationships that a busy London law firm doesn’t always leave time for.

We were also delighted to welcome some of our closest business partners from companies including Oceantide, ChaseEvans, Chestertons, Tai Bong, Chancery Consultants Ltd and Barrain London. A relaxed setting like this makes it easier to catch up, exchange ideas and strengthen the working relationships we value.


Table tennis tables with colleagues in the background


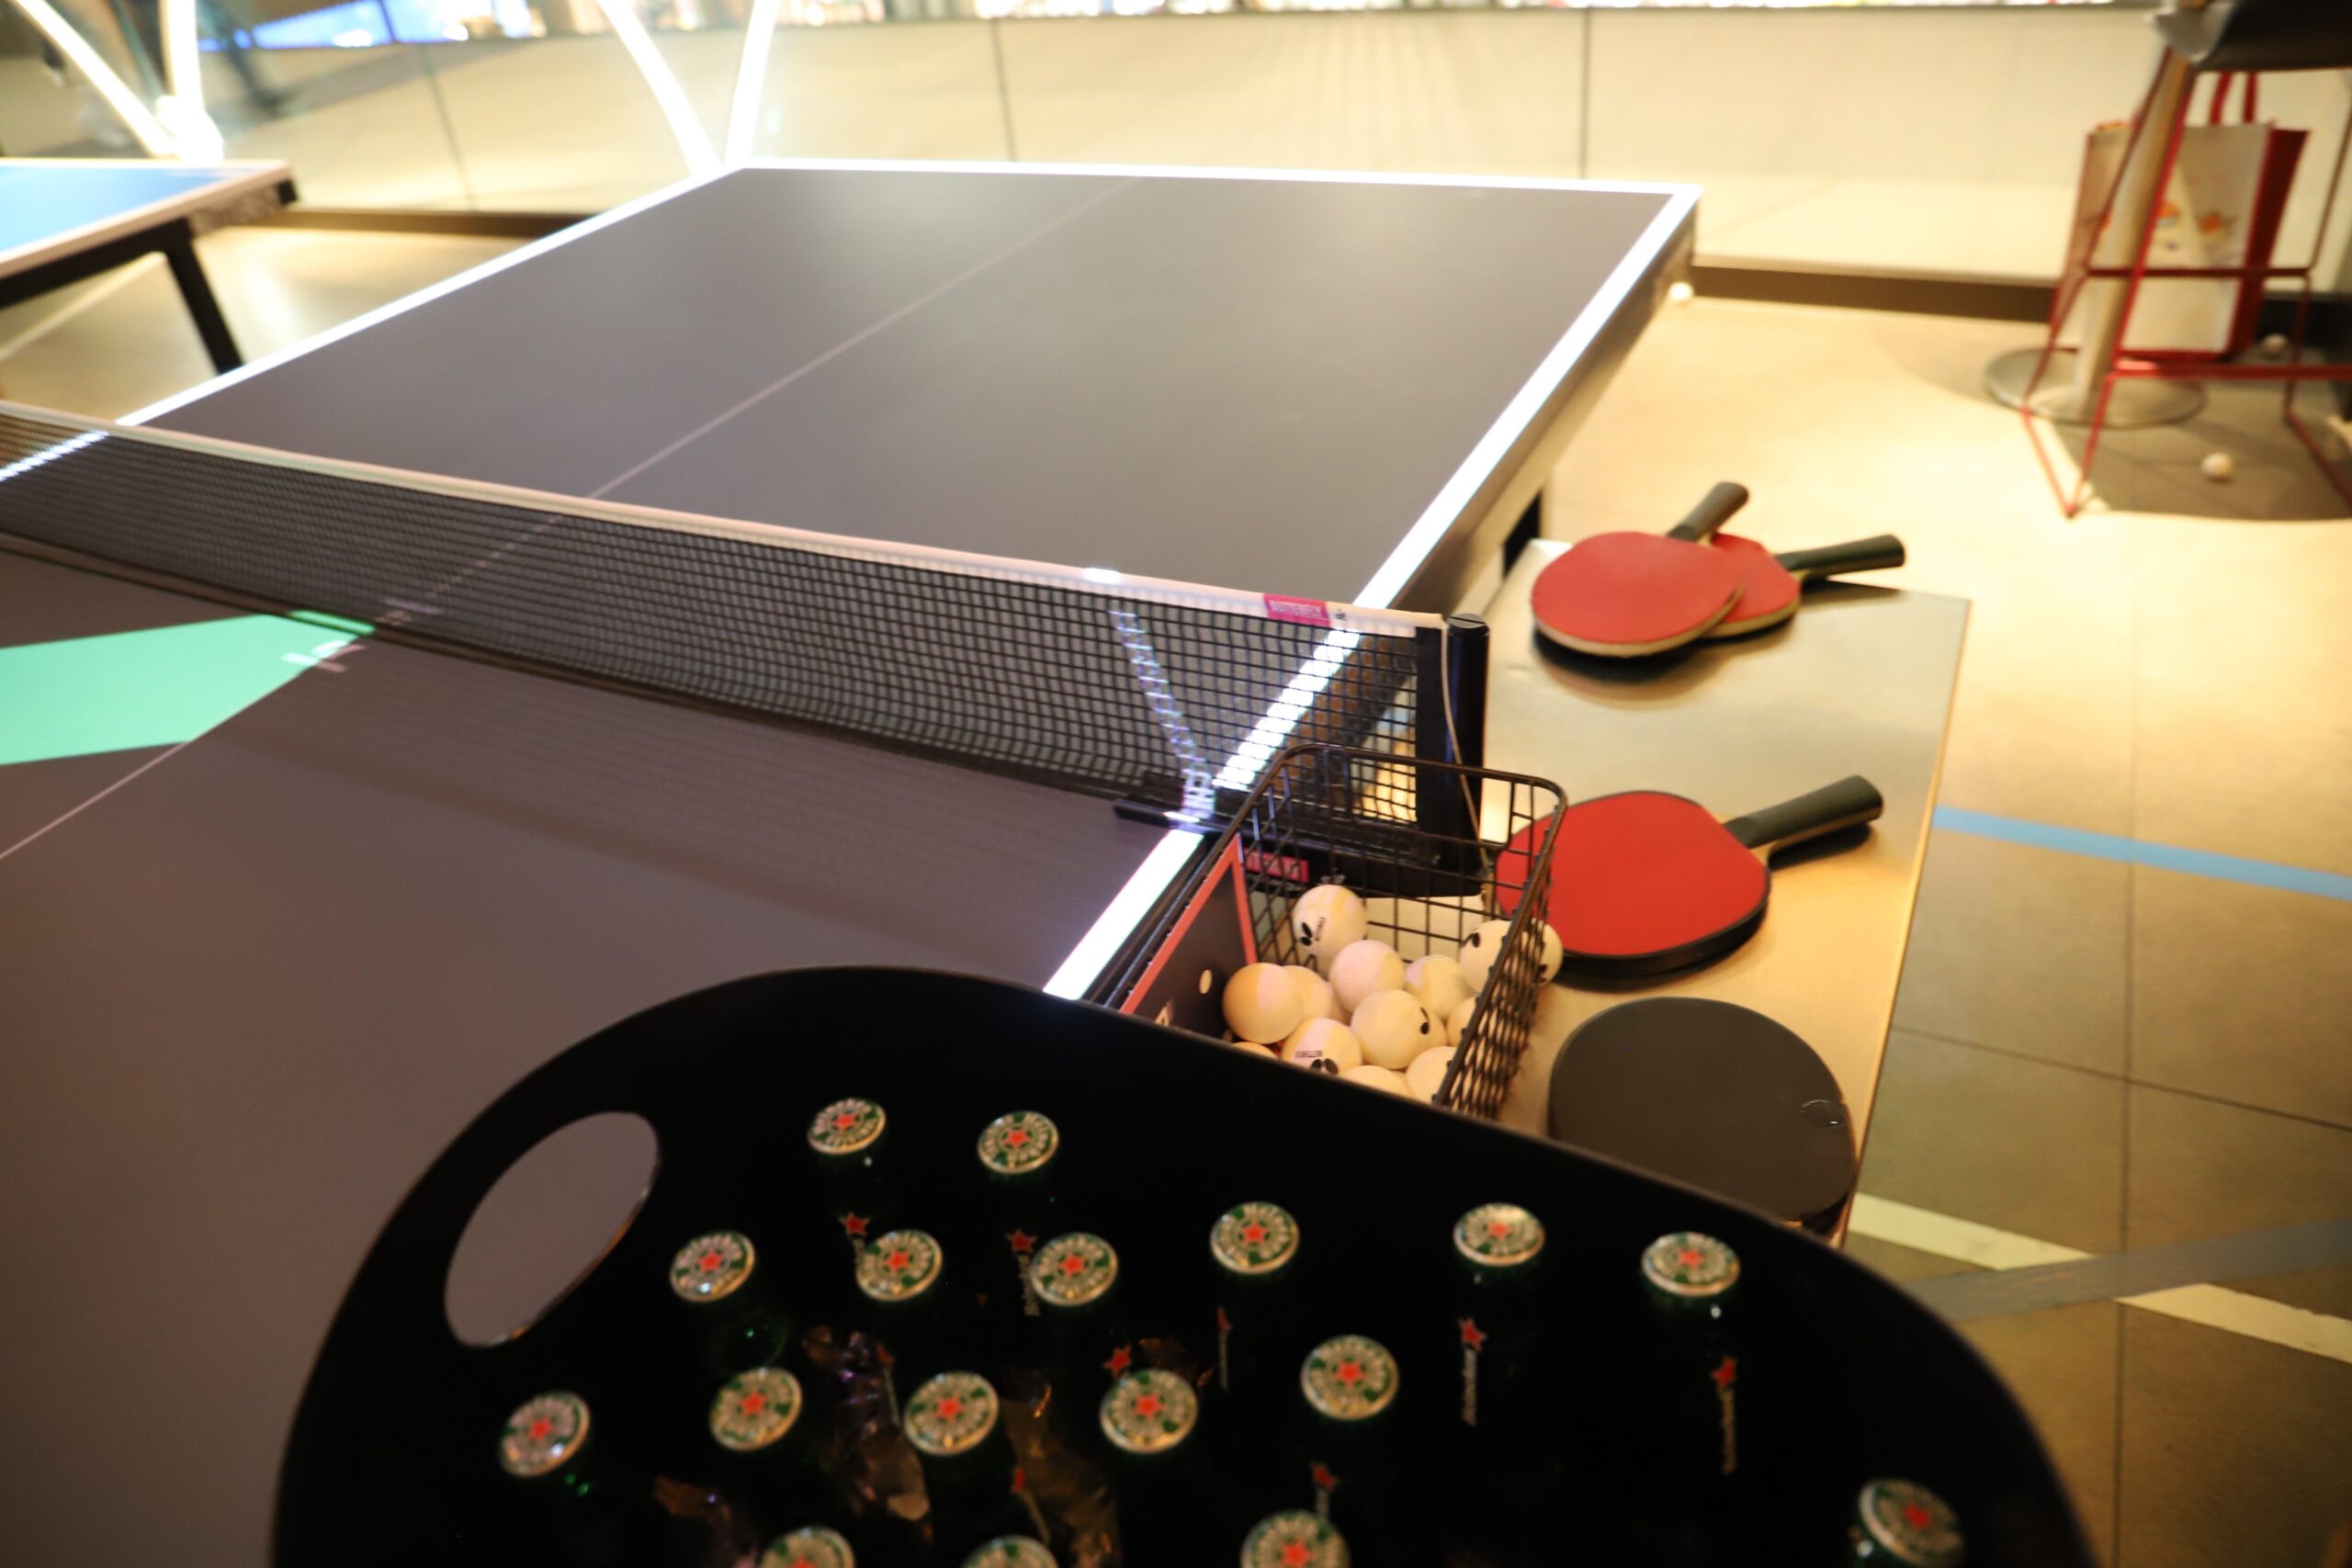
On arrival, we were met with beer, wine, food and more while everyone mingled. We then split into pairs to take part in a table tennis tournament organised by the friendly Bounce staff.

People playing table tennis

The tournament was highly competitive, with colleagues and business partners alike coming together to try and win.

Thank you to everyone who came, including our business partners. We are already looking forward to our next event, our Christmas social later this year.

You can find out more about our last Summer social here and our Spring social here.


Need legal advice? We’re here to help.

If you have questions about your situation or need advice on your next steps, our experienced legal team can help.

Call us on 020 7928 0276 between 9:30am and 6:00pm, or email [email protected].

You can also contact us online by completing our short enquiry form. Tell us a little about your situation and we’ll get back to you as soon as possible.

Not sure which service you need? Get in touch and we’ll help you identify the right team.
author avatar
James Cook

Have a question? Our friendly and experienced team are here to help.

Subscribe to our newsletter

We post weekly articles covering a variety of topics, including immigration, property, and more, so subscribe to our newsletter for the latest updates. 

Subscribe Newsletter Blog Sidebar

This field is for validation purposes and should be left unchanged.
Untitled(Required)