13 London Road,
London, SE1 6JZ
020 7928 0276
[email protected]

News and Insights

Pontins is a historic holiday park company, which at its height, had a number of parks up and down the country. It now runs just two, and recently found itself in hot water over a racial discrimination investigation by the Equality and Human Rights Commission (EHRC).


This investigation has resulted in Pontins being served with an unlawful act notice based on several clear breaches of the Equality Act 2010 for discrimination targeted towards Gypsies, Travellers, their associates, and those they suspected of being Gypsies and Travellers.


Keep reading to find out more about this case and to learn more about race discrimination law in the UK, as well as how your business can ensure that you comply with such laws.


Background


The origins of this report dated back to March 2020, when information was received from a whistle-blower stating that Pontins had discriminated against Gypsies and Travellers.  The information disclosed by the whistle-blower included an ‘Undesirable Guest List’, which featured 40 names of Irish origin. This was used to identify suspected Gypsy and Travellers guests in order for Pontins’ staff to more easily to cancel or refuse their bookings.


In February 2021, the EHRC entered into a section 23 agreement with Pontins as per the Equality Act 2006. This required Pontins to carry out an action plan and provide evidence of how they were carrying out prevention of future acts of discrimination against Gypsy and Travellers. However, just shy of a year later, the EHRC terminated the section 23 agreement due to Pontins’ breach of the terms.


The EHRC identified that Pontins had failed in its requirement to review its terms and conditions in order to assess whether they were either directly or indirectly discriminatory against Gypsies and Travellers. Furthermore, Pontins concluded that their list of surnames was justified and that it was not used for a discriminatory purpose.


A few months later, the EHRC launched an investigation which examined whether Pontins had committed unlawful acts of race discrimination. These included those that they perceived or suspected were either Gypsies, Travellers, are those who were associated with them such as friends or families.


What are the discrimination rules under the Equality Act 2010? 
 

Diversity and inclusion


As a holiday company, Pontins is deemed to be a service provider under the Equality Act 2010. Discrimination against guests can entail the following:


  • Refusal to provide a service
  • The terms on which a guest’s holiday is provided
  • Terminating the holiday
  • Subjecting guests to any other detriment


The racial discrimination discussed in this report focuses on whether Pontins committed unlawful acts of discrimination against Gypsies and Travellers. However, it also includes guests or potential guests that Pontins either perceived or suspected of being Gypsies or Travellers.


How is discrimination defined under the Equality Act 2010?


The nature of Pontins discrimination against Gypsies and Travellers was multi-faceted. The EHRC found Pontins to be responsibility for direct, indirect and associated discrimination, all of which are defined as unlawful under the Equality Act 2010. These distinct forms of discrimination are defined as follows:


Direct discrimination


Direct discrimination includes when a person discriminates against another person because of a protected characteristic. Or, if they treat a person with a protected characteristic less favourable than they treat others.


In the case of race-based direct discrimination, less favourable treatment includes segregating a person from a specific race from others.


Pontins committed direct discrimination based on their identification of Irish Travellers and use of systems and databases to ban Irish Traveller guests and their associates. This includes those who they perceived to be Irish Travellers, but may not have been.


Indirect discrimination


Indirect discrimination is slightly more nuanced, however the Equality Act defines it as being when a person applies to a person or a group of people a “provision, criterion or practice which is discriminatory in relation to a relevant protected characteristic” of that person or group. This puts that person or group of people with a protected characteristic at a disadvantage compared with someone who does not share that characteristic.


This type of discrimination is often more common in workplace environments where a company has applied a blanket policy. However, it would not be deemed indirect discrimination if:


  • there is a good reason for doing so that is not discriminatory, and
  • it is a proportionate and necessary way to achieve that aim.


Pontins were indirectly discriminatory towards Gypsies and Travellers based on their requirement for guests to be on the electoral roll.


Discrimination by association


Pontins were also found to be responsible for two acts of direct discrimination by association. This is defined as treating someone less favourable than another person because they are associated with a person who either is or is perceived to be of a protected characteristic. In this case, Irish Travellers or Gypsies.


Guest were refused services by Pontins due to their association with people who were, or were perceived to be Irish Travellers or Gypsies.


How did Pontins breach the EHRC?


A number of startling breaches of the Equality Act by Pontins were discovered by the EHRC. These included the following:


  • Instructing their call centre staff to listen out for Irish accents in order to supposedly identify Irish travellers as well as to decline or cancel their bookings
  • The creation of a list of common Irish surnames that they labelled as ‘undesirable guests’. This would be used to instruct staff to decline or cancel bookings made under those names.
  • Labelling Irish travellers and their associates as ‘undesirables’.
  • Maintaining a ‘banned guest’ list. This list was made up of people suspected of being Irish travellers and their associates by Pontins
  • Finally, Pontins were also found to have introduced rules in 2018 which required guests to be on the electoral register. This was a practise which was found to be discriminatory against Gypsies and Travellers


What must Pontins do next?


The EHRC investigation concludes with a number of measures which must be implemented by Pontins. Pontins must meet the following recommendations in accordance with the law:


  • Apologise to and engage with the Gypsy and Traveller community, acknowledging their corporate responsibility and committing to a zero-tolerance approach to discrimination.
  • Monitor booking cancellations and failures in order to identify future or remaining issues.
  • Review and update their policies and procedures to ensure they are not discriminatory.
  • Develop and deliver training, including equality training around their legal duty to not discriminate.
  • Remove terms that stipulate electoral roll checks.


As part of these recommendations, Pontins must produce an action plan by 5pm on 9th April 2024. As the action plan is enforceable in court, failure to do so will result in criminal sanctions for failure to comply.


How can businesses take measures to comply with anti-discrimination legislation?


It is a necessity for businesses to uphold their legal obligations and promote a fair and inclusive environment for all individuals.


There are actions that business owners can take to comply with such obligations. These include:


Policies and trainings: Implement clear policies prohibiting discrimination and providing equal opportunities for all employees and customers. Regular training for staff on diversity, equality, and inclusion is crucial.


Review Practices: Regularly review recruitment, promotion, and customer service practices to identify and eliminate any potential discriminatory barriers.


Consultation: Consult with employees, customers, and other stakeholders to understand their experiences and perspectives on equality and diversity within the business.


Monitoring and Reporting: Implement systems to monitor and report on equality and diversity issues within the business. This includes tracking recruitment, retention, and promotion statistics by protected characteristics.


Seek Advice: Seek advice from legal professionals or equality specialists to ensure compliance with EHRC regulations and to address any potential risks.


By proactively addressing equality and diversity issues within their businesses, owners can minimise the risk of breaching EHRC regulations and create a more inclusive and fair environment for all, which is vital for business in the modern world to succeed and thrive.


Our thoughts


The recommendations made by the EHRC towards Pontins are a comprehensive set of measures which, if followed, will address discrimination targeted towards Gypsies and Travellers.


The actions taken by the EHRC against Pontins are a reminder to businesses providing services of their duty to comply by the Equality Act 2010. Businesses should review their policies and practises to ensure that they are not discriminating, either directly or indirectly, against those with a protected characteristic.


At Lisa’s Law, we have a great track record of guiding businesses and employers in regulatory compliance, as well as extensive experience of advising on company policy, employment contracts and company handbooks.  Contact us today.


Have questions? Get in touch today!


Call us on 020 7928 0276, phone calls are operating as usual and we will be taking calls from 9:30am to 6:00pm.


Email us on [email protected].


Use the Ask Lisa function on our website. Simply enter your details and leave a message, we will get right back to you: https://lisaslaw.co.uk/ask-question/


For more updates, follow us on our social media platforms! You can find them all on our Linktree right here.

author avatar
James Cook

The Home Office has issued a new Statement of Changes in Immigration Rules HC 556 on 19 February 2024. The Statement makes a number of anticipated changes to the rights of care workers to bring dependents to the UK through the Health and Care Worker route, as well as changes to the various Ukraine schemes – including the closure of the Ukraine family scheme.

Mahfuz namecard


Below, I will highlight some of the key changes.


Care worker


Dependents of care workers will no longer be able to apply to join the main applicant in the UK from 11th March 2024. This applies in all cases where the main applicant has leave in either Standard Occupational Code (SOC) codes 6145 (Care worker) or 6146 (Senior care worker). The change will not affect those who are currently on a dependent visa, have children born in the UK or have applied for entry clearance before 11 March 2024.


All employers sponsoring care workers must have Care Quality Commission (CQC) registration from 10th March 2024. This means that an applicant applying for a skilled worker visa as a care worker must ensure that their employer has the above registration otherwise the visa will be refused.


The above has been introduced by making amendments to Appendix Skilled Worker, Appendix Skilled Occupations and Appendix Shortage Occupation List of the Immigration Rules. They come into force for applications submitted on and after 11 March 2024.


The Explanatory Memorandum states that the changes are being made ‘in response to high levels of non-compliance and worker exploitation and abuse, as well as unsustainable levels of demand’.


There have also been changes to the Ukraine scheme with the immediate closure of the Ukraine family scheme.


Have questions? Get in touch today!


Call us on 020 7928 0276, phone calls are operating as usual and we will be taking calls from 9:30am to 6:00pm.


Email us on [email protected].


Use the Ask Lisa function on our website. Simply enter your details and leave a message, we will get right back to you: https://lisaslaw.co.uk/ask-question/


For more updates, follow us on our social media platforms! You can find them all on our Linktree right here.
author avatar
James Cook

“Getting on the housing ladder”. It’s a phrase which for generations has been an aspirational one for many young people living in the UK. However, with wages struggling to keep up with inflation, a lack of housebuilding, and rapidly escalating property prices, it is widely acknowledged to be increasingly difficult to buy your first property. Many solutions have been put forward, with the latest being 99% mortgages.


This idea has been reportedly considered by the government and may be introduced in the Chancellor, Jeremy Hunt’s Spring Budget on 6th March. But are 99% Loan to Value (LTV) mortgages a good idea? In today’s article, we take a look at the idea of 99% mortgages, examining the advantages and disadvantages for first-time buyers.


What is a 99% LTV mortgage?


Simply put, a 99% LTV mortgage means that a lender (bank or building society) gives a buyer a loan which is worth 99% of the price they are buying a property for. This means that for a buyer, they only need to put up a 1% deposit. If a property is worth £250,000, they would only need to put £2,500 towards the deposit. This is a far lower deposit than would be needed for a 5% or 10% deposit for example. As a result, a property with a 99% mortgage is far more affordable in terms of getting on the property ladder.


Some lenders are already offering 100% mortgages, which mean that the buyer doesn’t need to put down a deposit at all. Most of these are guarantor mortgages, however there are some which are largely based on your rental payment history.


Advantages of 99% Mortgages


A major difficulty for those who want to go from renting to buying their own home is high rental costs. Many who are currently renting are paying increasingly high rent to their landlords, particularly in UK cities like London. This makes it difficult to save, even though those individuals would be paying less for their mortgage than they currently are by renting. Therefore, 99% mortgages would allow first-time buyers to save less before purchasing their property.


While 95% mortgages are still available through the mortgage guarantee scheme, meaning that the government will cover the costs if the lender loses money, these deposits can still be very hard to save for. The reason for this is that house prices have soared in recent years, and the average cost for a home is now £288,000 as of June 2023. Meanwhile, the average wages has struggled to keep up.


There are also positives to be had for lenders, with a potentially bigger market available to them. Nevertheless, there are also potentially disadvantages when it comes to 99% mortgages. Let’s discuss these now.


Disadvantages of 99% mortgages


Despite the obvious benefits of 99% mortgages, particularly for those people who are looking to get onto the housing ladder, there are also some negatives to bear in mind.


For one thing, a 99% mortgage will naturally have higher interest rates than a mortgage with a lower LTV percentage. As a result, these mortgage holders will be paying a greater total amount in order to pay off the mortgage than a product with lower interest rates.


Higher interest rates may also mean that for some, they may find that the product puts them under financial strain. However, for those who are already renting, this may still be either a negligible difference or a much lower amount compared with their previous monthly rental payments.


There is also the possibility that 99% mortgages could leave these mortgage holders in negative equity if housing prices were to fall. This means that the outstanding balance on  your mortgage is more than the house itself is worth. If this is the case, it can cause huge problems if you want to sell your home. Furthermore, it may also cause issues when your existing mortgage ends. Lenders don’t usually let mortgage holders switch to a new deal if they are in negative equity. Instead, they will usually be moved on to the lender’s standard variable rate, which tends to have a much higher interest rate.


Prior to the Great Recession of the late 2000s, banks were often lending 100% or sometimes even more of a property’s value. The financial crash resulted in thousands of mortgage holders being stuck in negative equity and stuck on high interest rates following the collapse of several lenders. Despite this, it is worth bearing in mind that the criteria for a mortgage from lenders is now much more stringent and based on affordability.


Finally, there has been concern from across the property industry over the impact that 99% mortgages could have on the market. With more people having the ability to buy a property, this could further increase demand while reducing supply if not enough new properties are built. After all, the lack of housing stock in the UK is already self-evident for many of those struggling to buy their first home.


Our thoughts


While the intentions of getting more people on to the housing ladder are a noble one, the idea of a government-backed 99 per cent mortgage scheme is not necessarily a way to address the root cause of the housing crisis. At the moment, there are a lack of affordable homes available, and this move would result in even greater competition between potential homeowners.


Nevertheless, despite the risks it may be a very popular move for young people, particularly in cities like London where the main difficulty with buying a home is saving enough for a deposit. A 99% government-backed mortgage would therefore potentially help to unlock a generation of new homeowners. We will wait and see whether the government decides to go ahead with this move in its upcoming Spring Budget, which will be the last one before the next General Election.


Have questions? Get in touch today!


Call us on 020 7928 0276, phone calls are operating as usual and we will be taking calls from 9:30am to 6:00pm.


Email us on [email protected].


Use the Ask Lisa function on our website. Simply enter your details and leave a message, we will get right back to you: https://lisaslaw.co.uk/ask-question/


For more updates, follow us on our social media platforms! You can find them all on our Linktree right here.
author avatar
James Cook

Recently, the government has announced changes to the visa rules in order to reduce immigration. The government has come under pressure due to the unprecedented levels of immigration since the Covid pandemic, which has seen net migration increase to over 700,000 per year. This has resulted in the government taking action to cut net migration to a lower level.


Mahfuz namecard


One of these changes includes stopping overseas care workers from bringing family members to the UK, effectively banning care worker dependants. Last year, 120,000 dependants came via this route, a sizeable number of the total number of immigrants. The government has decided to take action to ensure providers in England will only be able to sponsor migrant workers if they are undertaking activities regulated by the Care Quality Commission.


This change will come in force on 11 March 2024. It will affect care workers (SOC 6145) and senior care workers (SOC 6146). We recommend submitting applications to bring your dependants to the UK by 10 March 2024 at the latest.


If you have any questions, please feel free to contact us and we would be happy to help.


Have questions? Get in touch today!


Call us on 020 7928 0276, phone calls are operating as usual and we will be taking calls from 9:30am to 6:00pm.


Email us on [email protected].


Use the Ask Lisa function on our website. Simply enter your details and leave a message, we will get right back to you: https://lisaslaw.co.uk/ask-question/


For more updates, follow us on our social media platforms! You can find them all on our Linktree right here.
author avatar
James Cook

An important Court of Appeal case has reaffirmed the succession criteria for a tenancy when a joint tenant leaves a secure tenancy. Unlike assured shorthold tenancies, secure tenancies often allow for strong succession rights. This may allow family members such as spouses or children to succeed to the tenancy should the original tenant pass away.  This case also outlines the rights and status of landlords and tenants in situations where one of the joint tenants in a secure tenancy leaves a property. Furthermore, it addresses the issue of when surrender and regrant applies if a joint tenancy leaves a property.


But what happens when a joint tenant in a secure tenancy decides to leave a property? Well, normally this means that both joint tenants continue to be responsible for the rent. However, the case we shall be discussing today, Rahimi v City of Westminster Council, presents a more complicated situation.


This case focuses on an appeal by the grandson of a former tenant of a flat owned by Westminster Council. The grandson (the appellant in this case) was appealing against a decision which had reversed a previous judgement that held that the appellant’s grandmother was the sole tenant following the departure of her husband from the property.


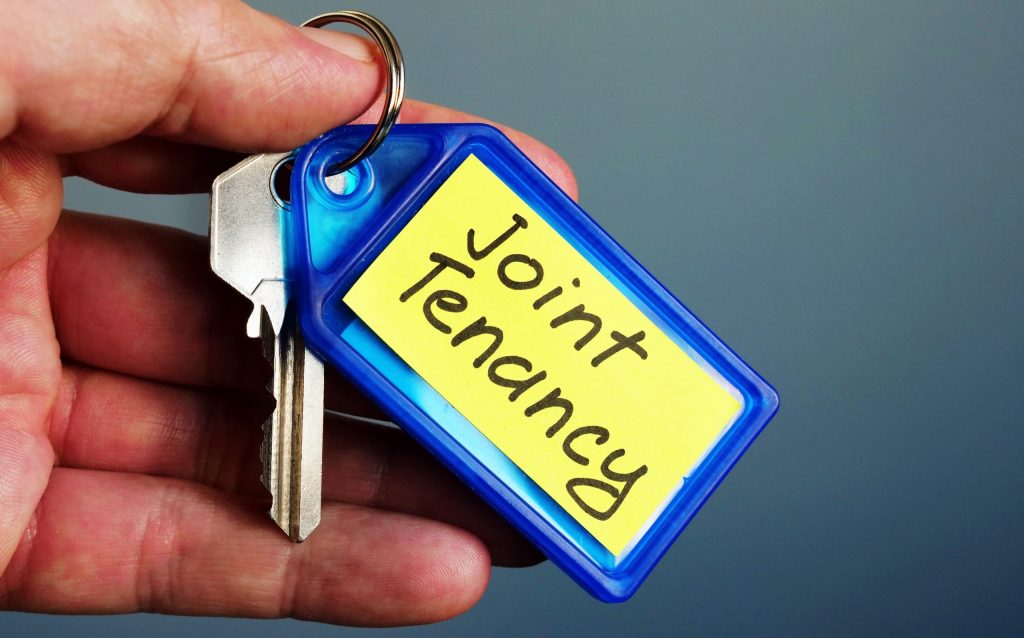
Hand holds key with Joint Tenancy inscription.


Background


To summarise the background of this case, the appellant (Mr Rahimi) was the grandson of a tenant (Mrs Hussain) who had originally rented the flat under a joint tenancy with her husband. The flat was owned by the local authority, Westminster Council. The husband left the property and became homeless, leaving the grandmother as the only occupant until her grandson, Mr Rahimi, arrived in the UK and started living with her.


Following Mrs Hussain’s death, Mr Rahimi defended his claim for possession on the basis that he had succeeded to the tenancy on Mrs Hussain’s death. However, this was dependent on the question of whether prior to her death, Mrs Hussain could be deemed a sole tenant. If she was a joint tenant, despite her husband leaving, succession would be prevented by the right of survivorship, which would mean Mrs Hussain’s estranged husband, Mr Kazam, would have been inherited sole tenancy by way of survivorship.


The trial judge had held that Mrs Hussain was the sole tenant granted to her by the local authority following Mr Kazam’s departure as a result of implied surrender and regrant, by way of Mr Kazam voluntarily moving out of the property. As a result, they held that the appellant, Mr Rahimi was entitled to succeed to the secure tenancy. However, on first appeal, the judge found that there had been no surrender of the joint tenancy and therefore no regrant. This was appealed by Mr Rahimi.


Decision


This appeal brings us to the subject case of this article. The main question which arose was whether the local authority had granted a new sole tenancy to Mrs Hussain with Mr Kazam’s permission.


It was found that:


  • There was no support for the finding by the trial judge that Mr Kazam had surrendered joint legal possession
  • Mrs Hussain remained liable for the rent
  • Mr Kazam made no request for the tenancy to be transferred solely to Mrs Hussain, nor was there evidence of the keys being returned
  • Leaving the property was not evidence of him relinquishing joint legal possession
  • There was also no evidence that Mr Kazam either consented to the grant of a new tenancy to Mrs Hussain, knew about any arrangement between her and the local authority, or that he had been excluded from the property
  • No evidence that Mrs Hussain had agreed to be solely responsible for the rent
  • There was therefore no evidence that Mrs Hussain had been granted a new sole tenancy by the local authority
  • Mrs Hussain had relied on her 2005 joint tenancy agreement when supporting her grandson, Mr Rahimi’s visa application in 2017


As a result of these findings by the Court of Appeal, it was concluded that Mrs Hussain had remained a joint tenant until her death. Mr Rahimi was therefore not entitled to succeed to this tenancy.


The justice who gave the lead judgment for the Court of Appeal, Lord Justice Lewison confirmed that the law is as follows: when a new tenancy is granted to a sole tenant, surrender and regrant would only occur in cases where the new tenancy is at the outgoing joint tenant’s request or with their consent.


Our thoughts


This important case clarifies the law on both succession of tenancies, as well as surrender and regrant in a secure tenant contract. It is not enough for a sole tenancy to be created if one of the joint tenants simply vacates the property. Instead, a new sole tenancy must be created by way of surrender and regrant between the landlord and tenant.


This underlines the importance of clear communication between landlords and tenants when it comes to their rental situation, particularly in joint tenancies where both parties are both jointly and independently liable for rent. If Mrs Hussain had been granted a new sole tenancy through surrender and regrant, this would have strengthened Mr Rahimi’s successions rights. If you require any advice or need help with your rental situation, contact us today and we will be happy to help.


Have questions? Get in touch today!


Call us on 020 7928 0276, phone calls are operating as usual and we will be taking calls from 9:30am to 6:00pm.


Email us on [email protected].


Use the Ask Lisa function on our website. Simply enter your details and leave a message, we will get right back to you: https://lisaslaw.co.uk/ask-question/


For more updates, follow us on our social media platforms! You can find them all on our Linktree right here.
author avatar
James Cook

The High Court has granted the migrant and refugee charity organisation, Refugee and Migrant Forum Of Essex & London (RAMFEL), permission to bring a judicial review of the government’s treatment of people with 3C leave immigration status.


When an applicant is applying to extend their stay in the UK in time, applicants are automatically granted 3C leave so that their existing rights are protected while their application is processed.


Currently, the government does not provide those on 3C leave with proof of their immigration status, which RAMFEL states has led people to have difficulties with employment, study courses and disability benefits.


RAMFEL’s 2022 report found that 17% of people on 3C leave suffered serious detriment. Based on available figures, as many as 40,000 people nationwide could be facing wrongful suspension from work each year.


The report made four recommendations to the government, including providing confirmation of a person’s rights and entitlements whilst on 3C leave.


The High Court will now consider whether the government’s conduct is unlawful.


This case will be heard on 19 and 20 March 2024. If the court considers that the government’s conduct is unlawful, this will put huge pressure on the government to provide people proper proof of their immigration status whilst on 3C leave.


My thoughts


Mahfuz namecard


I have seen this so many times with my clients over the years when they have submitted an in-time application to extend their stay in the UK and are waiting for a decision on their application. In my opinion, some employers have been excessively requesting my clients for updates on their application. This has led to me writing a letter to the employers and providing evidence that their application was submitted on-time and that they are automatically granted section 3C leave so that their existing rights are protected while their application is processed.


Having (in their opinion) not received sufficient proof of my clients’ immigration status whilst on 3C leave, some employers have unfairly stopped my clients from working until they receive evidence that their visas have been approved. There are measures put in place for the employers to make their necessary checks if an individual is able to continue to work while their applications are being processed. However, some employers have chosen not to use these measures that have been put in place for the necessary checks to be made.


I believe that the government’s conduct is unlawful. This is another clear example of the government’s hostile environment which aims to prevent those who cannot evidence their immigration status from working and accessing basic services, such as opening a bank account or accessing medical care.


I am happy that this matter has been put forward into the court and I hope that we will see positive changes from this. I have long been in favour of the idea of a document which is provided to people on 3C with leave proof of their status. This would state their existing rights such as employment, study courses and disability benefits which would be protected while their application is processed.


Have questions? Get in touch today!


Call us on 020 7928 0276, phone calls are operating as usual and we will be taking calls from 9:30am to 6:00pm.


Email us on [email protected].


Use the Ask Lisa function on our website. Simply enter your details and leave a message, we will get right back to you: https://lisaslaw.co.uk/ask-question/


For more updates, follow us on our social media platforms! You can find them all on our Linktree right here.
author avatar
James Cook

When is a poppadom not a poppadom? Well, according to the First-tier tribunal it’s when it’s actually a potato crisp. Sensations Poppadoms, a potato-based snack made by Walkers, was recently the subject of a tribunal deciding whether the product should benefit from zero rated VAT, the sales tax applied in the UK to certain products.


HMRC had originally decided in June 2021 that Sensations Poppadoms should be subjected to standard rated VAT (20%). This resulted in Walkers filing an appeal against the decision.


Let’s examine the basic rules regarding VAT on snack products, as well as the details of the case.


What are the rules regarding VAT on snack products?


This is a complex topic. VAT is generally not applied to food with the exception of certain products. These include products within Note 5 which are (similar to potato crisps, potato sticks, potato puffs) made from the potato, or from potato flour, or from potato starch” which are packaged for “human consumption without further preparation”. These were two of the main factors considered by the tribunal when it came to deciding whether the Sensations Poppadoms should be standard or zero rated. The similarity of the products to potato crisps, as well as their fiscal neutrality, was also considered when deciding whether the snacks should be standard VAT rated or not.


Let’s take a look at each of the individual factors and find out why the First-tier tribunal came to the conclusion that they did.


Decision


Human consumption without further preparation


Part of Walkers’ reasoning for the products not qualifying for “human consumption without further preparation” is their claim that the products were designed to be eaten with chutneys, dips, pickles, or as a side to the meal. On this basis, the products did require further preparation before being eaten. The reason they were arguing this is that products which qualify for human consumption without further preparation are usually standard VAT rated.


But is this a convincing argument? The tribunal found that there was nothing on the packaging to indicate that any preparation was required. Furthermore, their own packaging showed people eating them straight from the packet without any preparation.


As a result of this, the tribunal found that the products were indeed packaged for human consumption without further preparation.


Potato content of the products


On this factor, the tribunal was provided a detailed list of the ingredients of both the Lime and Coriander flavour, as well as the Mango and Chilli flavour Sensations Poppadoms.  Both flavours were found to contain around  17.5-18% potato granules, 17.5-18% potato starch, as well as 4.25% modified potato starch. The Tribunal noted that the consumer packaging for the poppadoms didn’t make any mention of modified potato starch in the ingredients list. The proportions of the potato granules and potato starch were also rounded down to the nearest whole number.


Walkers disputed the idea that potato granules should be included when determining whether a foodstuff should be considered under HMRC’s VAT rules. As a result of this, they submitted that the products should be regarded as only having 17% potato. Nevertheless, witness evidence submitted by HMRC contended that potato granules are pre-cooked dehydrated potatoes which should come under the term “the potato” as referred to under Note 5 mentioned earlier.


After considering all of the evidence, the Tribunal found that the products actually contain approximately 40% potato-derived ingredients. These took the form of potato granules, potato starch and modified potato. The proportion of potato in comparison with other ingredients was therefore considered significant in comparison with the products’ other ingredients. Despite this, although the Sensations Poppadoms contained enough potato-derived ingredients to be considered that they were made from these ingredients, the FTT noted that in isolation, this does not determine their similarity with potato crisps.


Similarity to potato crisps


Indian Style Crispy Thin Poppadoms Against a Blue Background


But what about the similarity of Sensations Poppadoms to potato crisps? This would also have an important bearing on the FTT’s decision. The Tribunal referred to a decision made by the Court of Appeal in HMRC v Proctor & Gamble UK [2009] EWCA Civ 407 which considered whether Pringles are similar to potato crisps.


While Walkers posted the question of traditional poppadoms are or are not similar to potato crisps, the tribunal found that this was not relevant to the appeal. Instead, they made the point that the question posed by statute was whether the products which are the subject of the appeal are similar to potato crisps.


The marketing was also used by the tribunal in order to determine the similarity of Sensations Poppadoms to potato crisps. Walkers argued that the products were called “poppadoms, unlike potato crisps.” However, the tribunal held that it nominative determinism is not a characteristic of snack foods, and that weight is not given to the names of the products for determining whether they are potato crisps. For example, no one would argue that “Monster Munch” is a food which is principally for monsters.


In terms of similarity, it was concluded that the ingredients, packaging, appearance and texture meant that the products could be considered as similar to potato crisps.


Fiscal neutrality


Finally, on the issue of fiscal neutrality, the idea that a tax should not distort economic behaviour, the FTT decided that applying the standard rate of VAT to the Sensations Poppadoms would not breach this principle. The fact that Walkers decided to market their product which was made from potato-based ingredients as a poppadom does not mean it should be treated the same as a poppadom not made from potato-based ingredients.


As a result of the above considerations, the tribunal found that the products are within Note 5 and therefore standard rated for VAT purposes. The appeal was therefore dismissed, however Walkers does have the right to appeal against the decision.


Our thoughts


While at first glance this might seem like a fairly trivial case, it provides important lessons for businesses in the food industry. Food and drink products which are for human consumption are usually zero-rated, however foods which may be deemed ‘less healthy’ are nearly always standard-rated (20%). This explains why the point over whether the Sensations Poppadoms were similar to potato crisps was such a bone of contention. Walkers will now be required to pay VAT on its range of Sensations Poppadoms.


If you want to learn more about how VAT rates are decided for food and drink products, click here.


Have questions? Get in touch today!


Call us on 020 7928 0276, phone calls are operating as usual and we will be taking calls from 9:30am to 6:00pm.


Email us on [email protected].


Use the Ask Lisa function on our website. Simply enter your details and leave a message, we will get right back to you: https://lisaslaw.co.uk/ask-question/


For more updates, follow us on our social media platforms! You can find them all on our Linktree right here.
author avatar
James Cook

It gives us great pleasure to welcome Matthew Wee to Lisa’s Law. Matthew joins the conveyancing team as a legal assistant, and we are delighted to have him here.


In terms of his background, Matthew is an LLB graduate of the University of Essex, having qualified with a First class with honours. His previous work experience includes being a Researcher at the University of Essex, as well as working as a member of the Conveyancing team at Zhong Lun Law Firm in London.


Matthew is fluent in both Mandarin and English, and can also understand and speak Cantonese at a conversational level.


In terms of his hobbies, Matthew loves to read and enrich himself in the arts – specifically in History and Philosophy. He also has a great affinity for languages, as he is actively studying Korean and Latin in his free time.


Have questions? Get in touch today!


Call us on 020 7928 0276, phone calls are operating as usual and we will be taking calls from 9:30am to 6:00pm.


Email us on [email protected].


Use the Ask Lisa function on our website. Simply enter your details and leave a message, we will get right back to you: https://lisaslaw.co.uk/ask-question/


For more updates, follow us on our social media platforms! You can find them all on our Linktree right here.
author avatar
James Cook

Recently, the government has introduced some changes to the skilled worker visa and the family visas. These changes have been introduced after the UK has experienced unprecedented levels of immigration.


Mahfuz namecard


Due to humanitarian reasons and duties, the UK has accepted a lot of people coming from countries like Ukraine, Hong Kong and Afghanistan. It has also experienced a growth in health and care worker visa, student and dependent applications. Net migration for the year up to June 2023 was 672,000, a huge increase on pre-pandemic levels.


The government has claimed that they may not be able to sustain public services and housing if the level of migration does not come down. As a result, they have taken actions to remedy this.


Skilled worker visa


businessman on phone in front of laptop


On 4 April 2024, the salary threshold for the skilled worker visa will increase from £26,200 to £38,700 for those arriving on the skilled worker visa route. This means visa holders who are already on the skilled worker visa route on or before 3 April will not be subject to such changes.


This will only affect visa applicants who are applying to work in the UK for the first time or visa applicants who are switching to the skilled worker visa route. It is important to note that people coming on the Health and Care worker visa will be exempt from this threshold. This is because the government wants more healthcare workers to come to the UK in order to provide the staff that our care sector and NHS needs.


We recommend visa applicants to submit their applications latest by 3 April so that they will not be affected by such changes.


Family visas


For family visas,  the government is increasing the minimum annual income requirement from £18600 to £38700. However, these changes will be incremental. The government will raise the income to £29000 on 11 April. The income threshold will be raised again to £34500 (no set date from the government) and finally to £38700 in early 2025.


To avoid such a raise, we suggest that applicants make an application on or before 11 April.


The government has also prevented students from bringing their dependants to the UK unless they are studying a multi-year postgraduate research degree to help bring down the migration level. Furthermore, they will also remove the right for care workers to bring dependants to the UK starting from 11 March 2024. This means that although they are not affected by the salary threshold, this change might affect the care workers who intend to come to the UK to work.


However, the government states that they want to ensure the applicants who come to the UK would genuinely support the social care system instead of how in their view people have often abused the route. Therefore, we suggest health and care worker applicants to apply for their dependants to come to the UK latest by 11 March.


If you have any questions regarding any of the above, please feel free to contact us and we would be happy to help.


Have questions? Get in touch today!


Call us on 020 7928 0276, phone calls are operating as usual and will be taking calls from 9:30am to 6:00pm.


Email us on [email protected].


Use the Ask Lisa function on our website. Simply enter your details and leave a message, we will get right back to you: https://lisaslaw.co.uk/ask-question/


For more updates, follow us on our social media platforms! You can find them all on our Linktree right here.
author avatar
James Cook

When you move to the UK, or spend part of your time in the UK, tax might not be at the forefront of your mind. Despite this, it probably should be. Thinking about tax now can save you from a costly tax bill later. Whether you have to and/or what you will need to pay tax on in the UK depends on a few key factors. Among these factors is your UK tax residency status.


At its core, tax residency in the UK is a relatively simple concept. In its simplest terms, if you reside in the UK for 183 days or more in a tax year then you are automatically a tax resident. Nevertheless, there are other factors which may or may not affect this that can complicate matters. In today’s article, we will seek to explain this and help you to establish whether you are a tax resident.


Being a tax resident means that you are generally liable for all income on UK-based employment, as well as non-UK employment and other possible sources of worldwide income and gains.


Being a non-resident means that you generally only pay tax on specific UK-source income and that UK tax is not paid on foreign income.


What determines your tax residency status?


The Statutory Residence Test (introduced in 2013) is the primary means of determining whether someone is resident in the UK for tax purposes. It contains a number of components which are used to determine whether you are a resident for UK tax purposes.


As well as being a resident if you spent 183 or more days in UK in the tax year, you may also be resident if:


  • your only home was in the UK for 91 days or more in a row – and you visited or stayed in it for at least 30 days of the tax year
  • you worked full-time in the UK for any period of 365 days and at least one day of that period was in the tax year you’re checking
  • You meet the sufficient ties test, including family, accommodation, work etc, spent 90 days or more in either of the previous two tax years, or spent more days in the UK than any other country


The number of ties you have with the UK and the length of time you have spent in the UK will determine whether you are a tax resident. This means that the more ties, the fewer number of days you will need to be in the UK to qualify as a tax resident. However, if you spend fewer than 46 days in the UK and were not a resident in the previous three tax years, then you will normally be non-resident. This means that even if a foreign citizen has immigration permission to reside in the UK, they may not in fact spend enough time in the UK to be a tax resident.


So, we have now established some of the general rules that determine whether you will be taxed in the UK as a resident. Now, let’s take a look at what income will be taxed and how it will be taxed.


How will my income be taxed?


Young caucasian couple hugging each other doing family accounting using laptop at home


Being resident in the UK means being liable to pay income tax and capital gains tax. While the former is fairly self-explanatory, capital gains tax refers to tax on the profit of an asset you sell or dispose which has increased in value. You could pay it on personal possessions worth £6000 or more other than your car, as well as a second home, business assets etc.


Being a resident in the UK means that you will generally be required to declare and pay income tax on all income from outside the UK. Furthermore, UK land and buildings may also be subject to capital gains tax and is not something which is affected by residence status.


The exceptions to the above are those who are remittance basis users, which prevents non-UK income and assets being subject to UK tax as long as they are not brought into the UK directly or indirectly. This is only available to those who are not domiciled in the UK, but are resident here. Click here for more information about remittance basis.


Income tax


Being employed means that you will be subject to income tax, which for the vast majority of people in the UK is paid at source via the PAYE (pay as you earn) system. This is quite simple as it will be done for you by your employer, however it is still worth checking that your tax code is correct. For others, including those who are self-employed, you will not be taxed at source, and may have to complete a self-assessment tax return with HMRC on an annual basis. The deadline for the 2022/2023 tax year is 31st January 2024.


Capital gains tax


Capital gains will also be taxed in the event that you are tax resident in the UK and sell foreign assets subject to the capital gains tax, such as property or investments. This will be paid on the value of any gain which exceeds £6,000 until April 2024. Those who are remittance basis users will only pay capital gains tax on any foreign gain which is remitted to the UK but they will lose the annual exemption amount.


Our thoughts


It is always worth speaking to a tax expert when moving from another country to the UK beforehand. The tax laws here can seem confusing to a newcomer, and by speaking to someone this ensures that any nasty surprises are avoided later on! Lisa’s Tax specialises in providing tax consultancy to individuals, us today to learn more.


Have questions? Get in touch today!


Call us on 020 7928 0276, phone calls are operating as usual and will be taking calls from 9:30am to 6:00pm.


Email us on [email protected].


Use the Ask Lisa function on our website. Simply enter your details and leave a message, we will get right back to you: https://lisaslaw.co.uk/ask-question/


For more updates, follow us on our social media platforms! You can find them all on our Linktree right here.
author avatar
James Cook

Have a question? Our friendly and experienced team are here to help.

Subscribe to our newsletter

We post weekly articles covering a variety of topics, including immigration, property, and more, so subscribe to our newsletter for the latest updates. 

Subscribe Newsletter Blog Sidebar

This field is for validation purposes and should be left unchanged.
Untitled(Required)